Tag Archives: Investor reachouts

General partner profiling has emerged as a critical component of investment decision-making because institutional investors face challenges in selecting the right managers, managing risk, and achieving consistent returns on investment. General partner profiling is not simply a matter of reviewing performance metrics. Limited partners (LPs) must understand a manager’s investment discipline, leadership capabilities, operational expertise, and ability to deliver returns across different business environments. The McKinsey Global Private Markets Report 2026 states that total capital raised by closed-end private equity funds worldwide declined by 17% to $616 billion in 2025, whereas deal value increased by 19% to $2.6 trillion. With liquidity declining and holding periods lengthening, investors are being prompted to scrutinize fund managers more closely.

General Partner Profiling: Market Trends and Growing Importance

Competition in private capital markets has been growing, making general partner profiling increasingly important to institutional investors. Changing fundraising dynamics, limited liquidity, longer holding periods, and evolving LP expectations require investors to assess fund managers on past performance alone.
General Partner Profiling

General Partner Profiling: Market Trends and Growing Importance

Changing Fundraising Dynamics

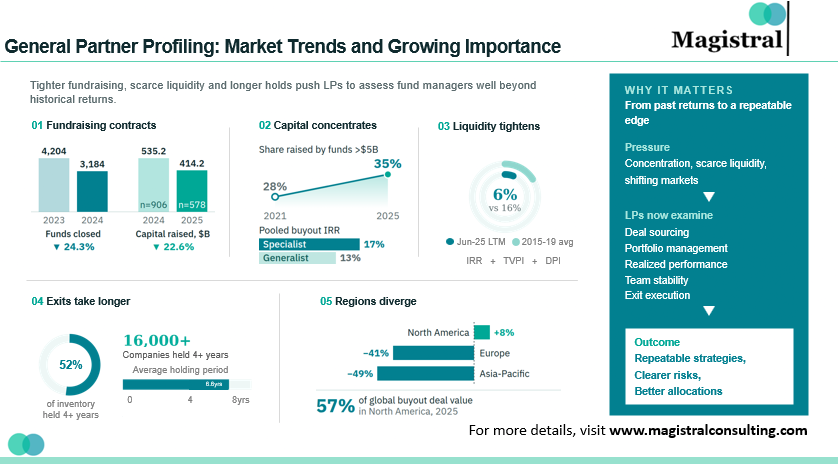
The fundraising environment has deteriorated because of higher financing costs and slower distributions of proceeds. According to Preqin, 3,184 funds closed in 2024, compared with 4,204 in 2023, representing a decline of 24.3%. In 2025, PitchBook data showed that 578 funds raised $414.2 billion, compared with $535.2 billion raised by 906 funds in 2024. Regional dynamics also differed: according to McKinsey research, fundraising activity grew by 8% in North America in 2025 but declined by 41% in Europe and 49% in Asia-Pacific.

Increasing Fundraising Concentration

More capital is flowing to managers with established track records. McKinsey reports that funds over $5 billion raised 35% of all fundraising in 2025 versus 28% in 2021. Smaller specialist managers differentiate themselves through focused expertise: McKinsey found that specialist buyout funds achieved an aggregated IRR of 17% versus 13% of generalists. LPs therefore need to assess whether a manager’s size, sector focus, or specialization provides a sustainable competitive advantage.

Greater Focus on Liquidity and Performance Metrics

LPs are placing greater emphasis on exits and capital returns rather than on valuations alone. McKinsey estimates that DPI as a proportion of AUM was just 6% during the year to June 2025 versus the average 16% during the 2015-19 period. This indicates that LPs should consider IRR, TVPI, and DPI when assessing both investment performance and the return of capital.

Longer Holding Periods and Exit Challenges

Another important factor in assessing fund managers is the extended time before an exit. As per McKinsey, there have been 16,000 portfolio companies worldwide that have had an investment tenure greater than four years, which constitutes 52% of the inventory that has been funded through buyouts. The average holding period reached 6.6 years in the year 2025. LPs must therefore analyze how GPs manage portfolio companies during extended holding periods and how they address exit planning, valuations, and conflicts of interest.

Regional Differences and Investment Opportunities

A manager’s geographic exposure should be assessed. North America accounted for 57% of the global deal value of buyouts in 2025. Europe offers opportunities in industrial consolidation, infrastructure, and the energy transition, while APAC offers opportunities linked to consumption growth and technological innovation. Investors should determine whether a GP has the regional capabilities required to execute its strategy.

Why These Trends Matter for Investors

Fundraising concentration, liquidity concerns, and shifts in the business environment have complicated fund manager selection. Past returns remain important, but investors increasingly evaluate deal-sourcing capabilities, portfolio management, historical performance, personnel stability, and exit processes. A structured general partner profiling approach can help limited partners identify managers with repeatable strategies, recognize possible risks, and make better allocation decisions.

General Partner Profiling: Core Evaluation Framework

Proper general partner profiling involves not only the financial performance of the fund but also the evaluation of its leadership, investment approach, governance, and operational capabilities. This comprehensive analysis enables investors to identify the strengths and possible risks associated with the manager.

Investment Track Record and Performance Attribution

A fund manager’s past performance is a useful starting point, although it never tells the whole story. LPs should evaluate performance on a deal-by-deal basis and consider metrics such as valuation at entry, leverage, value creation, holding periods, multiples of exit, and performance realized. Losses, write-offs, and performance relative to comparable funds also help distinguish skill from luck.

Sources of Value Creation

Understanding how a manager creates value is essential. LPs should evaluate the historical roles of leverage, multiple expansion, and operational improvements in a fund’s performance. Sources of return that worked well in the past may become less effective as market conditions change, increasing the importance of operational capabilities.

Leadership Experience and Team Stability

The experience and stability of the investment team affect fund performance. LPs should investigate the backgrounds of the senior leaders, the responsibility of the investment committee, employee turnover, succession plans, and whether they depend too much on certain individuals. LPs should also check whether the people who made the investments in the past work at the firm now.

Investment Strategy and Portfolio Construction

Investors need to determine whether a fund’s stated investment philosophy is consistent with its historical investments and demonstrated capabilities. Key considerations include target sectors and geographies, transaction size, sourcing capabilities, use of leverage, and portfolio concentration. Any change in investment philosophy should be supported by relevant experience and the capability to execute the revised strategy.

Governance and Alignment of Interests

Good governance contributes significantly to accountability and the alignment of interests between GPs and LPs. The evaluation process should consider management fees, carried interest, GPs’ contribution towards capital, conflicts of interest, valuations, and investment committees, among other factors. Investors should also assess co-investments and reporting procedures when evaluating alignment of interests.

Operational and Regulatory Oversight

A manager’s operational capabilities should form part of the assessment. These capabilities include fund administration, financial reporting, cybersecurity and information protection, compliance and valuations, and risk management.

Reputation and Stakeholder Relationships

References from current investors, portfolio company management, former staff members, lenders, and advisory firms can provide insights beyond past financial performance. Well-structured reference checks allow LPs to evaluate a manager’s communication, decision-making, integrity, and handling of difficult situations throughout the investment process.

A comprehensive general partner profiling process enables investors to look beyond past financial performance by assessing a manager’s investment approach, leadership, governance, operational capabilities, reputation, and stakeholder relationships.

General Partner Profiling: Technology and Analytical Strategies

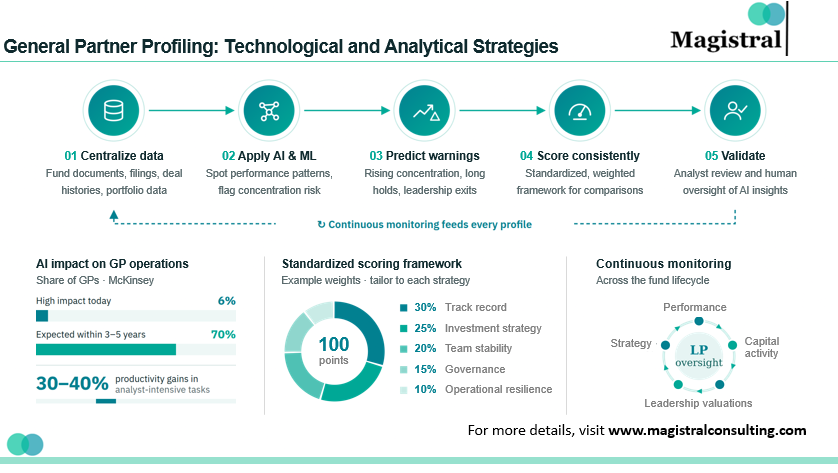
Tools and technologies such as AI, machine learning, and centralized investment databases can make general partner profiling faster, easier, and more efficient. Investment databases allow LPs to combine fund documentation, regulatory disclosures, transaction history, and other portfolio-related information when conducting thorough manager evaluations.
General Partner Profiling

General Partner Profiling: Technological and Analytical Strategies

Artificial intelligence can identify patterns in investment results, detect concentration risks, and generate insights from large volumes of investment data. According to McKinsey, only 6% of general partners consider the use of artificial intelligence to have a high impact on their business processes at the moment, but 70% of GPs expect high impact within the next 3-5 years, and a 30%-40% increase in productivity is reported in analyst work.

Predictive analytics can help identify warning signs such as portfolio concentration growth, holding period growth, and leadership transitions. Standardized scoring models based on criteria including track record (30%), investment philosophy (25%), team stability (20%), governance (15%), and operational flexibility (10%) can help LPs compare managers effectively, although different investment strategies may require different weightings. Analysts should always oversee and validate AI-supported analysis.

How Magistral Consulting Supports General Partner Profiling

Successful general partner profiling requires well-structured research, financial analysis, and continuous monitoring. Magistral Consulting supports investment teams through manager mapping, investment strategy research, performance record analysis, portfolio and financial performance comparisons, and due diligence assistance. Its analytical services also include organizing manager data, assessing risks, identifying information gaps, and creating performance dashboards and monitoring reports.


About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author
Tanya is an investment-research specialist with 6 + years advising venture-capital, private-equity and lending clients worldwide. A Stanford Seed alumnus with an MBA and an Economics (Hons) degree, she heads project teams at Magistral Consulting, delivering financial modelling, due-diligence and deal support on 3,000 + mandates. Her blend of rigorous analytics, sharp project management and clear client communication turns complex data into actionable investment insight.


FAQs

What is General Partner Profiling in private equity?

It is the systematic assessment of a fund manager's performance, investment strategy, leadership, governance, operational capabilities, and risk characteristics. LPs use the findings to support manager selection, investment commitments, and ongoing oversight.

Why do limited partners evaluate general partners?

Limited partners evaluate managers to identify investment expertise, assess potential risks, understand alignment of interests, and determine whether a manager's strategy matches their portfolio objectives.

Which metrics are most important when evaluating a fund manager?

Common measures include internal rate of return, total value to paid-in capital, distributions to paid-in capital, investment multiples, realized losses, and performance relative to comparable funds. In McKinsey's January 2026 LP survey, IRR remained the leading metric, with DPI and MOIC tied for second. Qualitative factors such as leadership stability and governance are equally important.

How can artificial intelligence improve manager evaluation?

AI can help organize large investment datasets, analyze documents, identify performance patterns, and highlight potential risk indicators. Human analysts still need to verify the information and interpret findings within the relevant investment context.

How often should investors review existing fund managers?
Investors typically review quarterly fund reports and conduct more detailed assessments periodically or when significant developments occur. Leadership departures, strategy changes, deteriorating performance, or governance concerns may warrant additional reviews.


There has been increased competition, institutionalisation and data usage in private capital. There is a need for the GPs to offer more to the LPs than just performance figures. Some of the information needed includes consistency in reporting, analysis at the level of the portfolio, performance information, capital accounting, market commentaries, among others.

Such an environment is generating increasing opportunities for LP communications outsourcing.

LP communications outsourcing entails outsourcing repetitive investor communications and reporting processes to specialist external personnel while the GP keeps control over the investor relations, messaging and sign-offs. Tasks could include quarterly investor reports, LP letters, performance reporting, capital calls/distributions, investor presentations, data room management, DDQs, fundraising materials and CRM management.

Market statistics for LP communications outsourcing do not exist. However, current trends in private equity markets, outsourcing, fundraising and reporting standards explain why there is an increasing demand for such services.

Why LP Communications Outsourcing Is Becoming Important

Private market financing has become much more selective in nature.

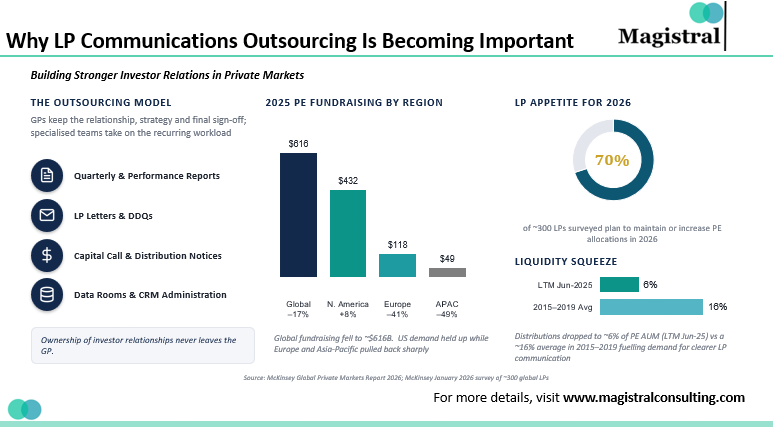
As mentioned in the McKinsey Global Private Markets Report 2026, the global total of fundraising by closed-end private equity funds decreased by 17 percent compared to the previous year to stand at $616 billion in 2025. Geographical differences were notable as fundraising in North America grew by 8 percent to $432 billion, while in Europe it decreased by 41 percent to $118 billion.

LP Communications Outsourcing

Why LP Communications Outsourcing Is Becoming Important

However, there is still strong interest among investors in the asset class. According to McKinsey’s survey conducted in January 2026 among approximately 300 global LPs, almost 70% planned to maintain or grow their private equity investments in 2026.

That presents a significant issue for GPs.

There is capital, but investors are becoming pickier about where it goes. Performance is important, but strategic communications, portfolio changes, value creation, liquidity, risk, and performance attribution may increasingly become factors in the entire LP experience.

GPs need a way of handling investor relations that does not take investment professionals away from their work.

Liquidity Pressure Is Increasing the Need for Better LP Communication

Liquidity is one of the most powerful influences on GP-LP relations.

According to McKinsey, distributions as a share of total private equity assets under management stood at about 6% for the year ended June 2025 compared to an average of about 16% from 2015 to 2019. Distributions as a share of five-year rolling DPI was about 10%, the lowest on record.

This has made DPI more relevant for LPs. McKinsey found that DPI is now as important as MOIC, with both being the second-most-important metrics LPs consider when allocating to GPs, after IRR.

In such cases where distributions remain constrained, communication becomes all the more relevant.

LPs need to be informed about why assets are being held for longer, the operational progress that portfolio companies are making, changes in valuations, exit options, and how liquidity might improve in the future.

Effective LP communications outsourcing goes beyond just reporting numbers and involves explaining the numbers.

What Does LP Communications Outsourcing Include?

The scope of LP communications outsourcing can cover much of the recurring investor-relations workflow.

LP Communications Outsourcing

What Does LP Communications Outsourcing Include?

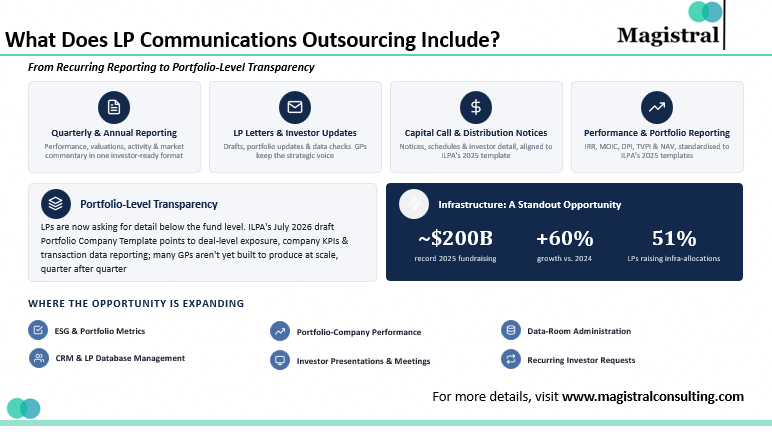
Quarterly and Annual Investor Reporting

Quarterly reports including portfolio performance, performance of individual funds, investment activities, valuations, operational updates, realised investments, pipeline status, and market insights may be prepared by external parties.

The information may be gathered from the fund administrators, financial teams, investors, and portfolio companies and then formatted and presented in a consistent manner for investors.

LP Letters and Investor Updates

LP letters involve both numbers and communication.

LP communications outsourcing process may involve preparation of draft letters, obtaining portfolio information, analysing movements in performance, preparing charts and tables, comparing numbers with raw data, and ensuring consistency across all reporting materials.

The GP may be in charge of the strategic commentary and final communication.

Capital Call and Distribution Communications

Fund capital calls and distributions are among the most common areas where there is interaction between the fund and the investors.

The updated ILPA Capital Call & Distribution Template was introduced in September 2025 by the Institutional Limited Partners Association (ILPA).

Notice preparation, support schedules, investor data, distribution details, and all related communication processes can be handled by external parties.

Performance and Portfolio Reporting

Increasingly, LPs have been demanding comprehensive details regarding IRR, MOIC, DPI, TVPI, NAV, portfolio company performance, value creation and investment-specific developments.

The increasing need for standardisation is reflected in industry efforts. ILPA has come out with an upgraded Reporting Template and a Performance Template in 2025 to enhance quarterly reporting consistency in private equity. This upgraded Reporting Template is meant for funds within their investment periods as at Q1 2026 and those starting their operations from 1 January 2026.

This presents chances for outsourced teams specialised in gathering, verifying, formatting and presenting details about funds.

Growing Demand for Portfolio-Level Transparency

Expectations in terms of reporting are changing to get more detailed information from each individual portfolio company.

In July 2026, ILPA came up with a draft of an update for its Portfolio Company Template and mentioned that LPs are recognising portfolio company data as a need for further transparency. The template will include deal level exposure, company specific KPIs, and investment transaction data.

For GPs who manage hundreds of investments in various funds, gathering such data on a quarterly basis becomes a challenge.

A reporting team can develop a process for obtaining, verifying, updating, and presenting the company-level data to investors.

Opportunities in LP Communications Outsourcing

The potential for LP communications outsourcing exists in private equity, venture capital, private debt, real estate, infrastructure, and various other alternative investments.

An especially good case in point would be infrastructure. According to McKinsey, there has been an all-time high of nearly $200 billion of infrastructure fundraising in 2025, an increase of nearly 60% over 2024. In their survey, it was seen that 51% of LPs planned to invest more in infrastructure over the coming three years.

This opportunity is thus being created in:

  • quarterly and annual investor reporting;
  • portfolio-company performance reporting;
  • DDQs and fundraising documentation;
  • capital calls and distribution notices;
  • investor presentations and LP meeting materials;
  • data-room administration;
  • ESG and portfolio metrics;
  • CRM and LP database management; and
  • recurring investor information requests

LP Communications Outsourcing Services Offered by Magistral Consulting

LP communications outsourcing services are meant to ease the burden on investor relations staff within companies while enhancing the consistency and accuracy of LP communications outsourcing.

LP Reporting and Investor Updates

Magistral supports quarterly and annual LP reporting, investor letters, portfolio updates, fund performance summaries, valuation changes, and market commentary in clear and consistent investor-facing formats.

Fund and Portfolio Performance Reporting

These metrics include IRR, MOIC, TVPI, DPI, NAV, KPIs of portfolio companies, among others, and are used to provide the necessary information for regular LP reporting.

Fundraising and Due Diligence Support

Magistral supports the production of DDQs, RFPs, pitches, fund presentations, track record analysis, investment cases, factsheets, and other documents needed throughout the fundraising and due diligence process.

Capital Calls, Distributions and Data Room Support

The team helps to provide support for communication regarding capital calls and distributions, including scheduling, investor relations, and the organisation of the investor data room and fundraising documents.

LP Database and Dedicated IR Support

Magistral provides LP database management, CRM management, investor profiling, communication monitoring, follow-ups, meeting documentation, and fundraising pipelines. Dedicated analysts can also serve as an extension of the company’s own internal investor relations departments.


About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author

Dhanita is a BD and Marketing professional with 6+ years’ experience in sales strategy, growth execution, and client acquisition; credentials include Stanford Seed (Stanford GSB), an MBA from USMS–GGSIPU, and a B.Com (Hons) from the University of Delhi. Expertise spans market research and opportunity mapping, sales strategy, CRM, brand positioning, integrated campaigns, content development, lead generation, and analytics; currently oversees business development calls and end-to-end marketing operations


FAQs

What is LP Communications Outsourcing?

LP communications outsourcing involves delegating recurring investor reporting, performance updates, fundraising documentation, and other LP communication activities to specialised external teams

What activities can be outsourced in LP communications?

Common activities include quarterly reporting, LP letters, performance reporting, DDQs, RFPs, capital call and distribution notices, investor presentations, data-room management, and CRM administration

Why do fund managers prefer LP communications outsourcing?

LP communications outsourcing helps fund managers reduce administrative workload, improve reporting consistency, access additional analytical capacity, and allow internal IR teams to focus on investor relationships and fundraising

Which investment firms can use LP communications outsourcing?

Private equity, venture capital, private credit, real estate, infrastructure, hedge funds, and other alternative investment managers can use outsourced LP communication support

Does outsourcing replace the internal investor relations team?

No. Outsourcing typically supports the execution-intensive parts of investor relations, while internal teams continue to manage LP relationships, strategic messaging, fundraising discussions, and final approvals


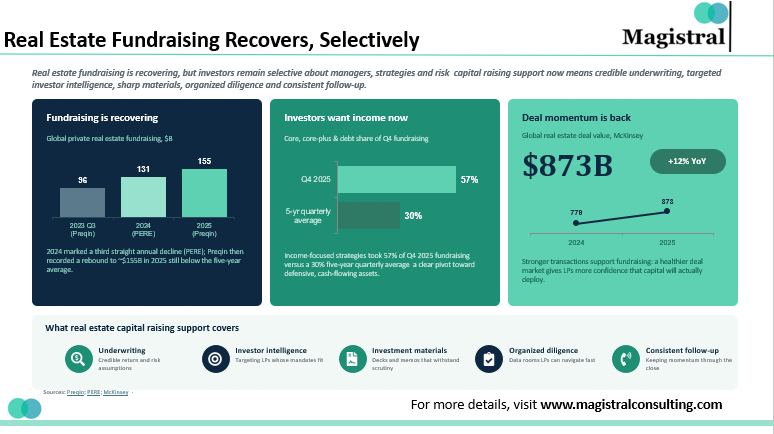
Fundraising for real estate investments is on the rebound, yet investors are still selective when it comes to the fund managers, strategy and risk profile. According to Preqin, fundraising for global real estate investments has grown to approximately $155 billion in 2025 compared to 2024 and is still below the average of the past five years. According to McKinsey, transaction momentum is also on the rise with the value of global real estate transactions growing to approximately $873 billion in 2025, an increase of about 12% year over year.

In this context, real estate capital raising services require much more than just maintaining a list of potential investors. They require credible underwriting, investor research, investment materials and follow-up to turn a good idea into a good investment.

Real Estate Capital Raising Support in a Selective Market

Fundraising conditions improved in 2025, though capital flow was unevenly distributed among fund managers and investment strategies. There is an increased preference for differentiated deals, solid platforms, and management with the ability to show how returns will be created.

Real Estate Capital Raising Support

Real Estate Fundraising Recovers, Selectively

Fundraising Is Recovering

Private real estate investment fundraising faced hard times after the last market peak. PERE reported that fundraising dropped to $131.1 billion in 2024, which became the third annual decrease. Preqin noted separately that $96 billion had already been raised until the third quarter of 2024. Fundraising conditions improved in 2025. Preqin noted approximately $155 billion of global real estate fundraising in 2025. Income-based strategies, such as core, core plus and real estate debt accounted for 57% of fourth quarter fundraising as opposed to 30% average five-year quarterly numbers. The data indicate that investors are back, yet with new priorities.

Hence, the managers must have real estate capital raising support services to link their strategy with current investors’ needs, not just rely on general market improvement. Financial credibility is extremely significant. Real estate financial modeling is quite detailed and helps managers prove how leverage, occupancy, rental increases, operating expenses and exit assumptions influence profitability.

Transaction Activity Is Improving

The field of real estate capital raising support is also aided through reclaiming transaction markets. According to McKinsey, there were $873 billion of global real estate deal values in 2025, which was an increase of approximately 12 percent compared to 2024. Nonetheless, there were significant disparities depending on the property type. Specialized real estate constituted approximately 14 percent of global deal volumes. There was an increase in deal activity in data centers by approximately 37 percent, and office deals increased by approximately 17 percent.

In the United States, there was an increase in deal activity for Class A offices by approximately 34 percent. This becomes significant while making a presentation for an investment opportunity as well as real estate capital raising support.

Capital Is Becoming More Concentrated

Fundraising recovery is not equal across all managers. McKinsey found that the top 20 managers were able to generate 51% of the trailing five years closed-end real estate fundraising as of 2025. In addition, approximately 17% of institutions indicated they would be reducing their number of managers. This represents a tougher landscape for emerging and mid-sized managers without the prestige of the largest platforms; these managers have to have a differentiator, transparency, strong underwriting process and proof of execution to separate themselves. Capital raising skills can assist these managers to turn those attributes into an investment product.

Real Estate Capital Raising Support Across the Investor Journey

Real estate capital raising support does not involve just one pitch or discussion. It is a process that entails identifying, qualifying, engaging, due diligence, investment committee decision-making and commitment of investors.

Investor Mapping Improves Outreach

A long list of investors is not always an indication of good fundraising. Managers must stratify potential investors according to geography, type of asset, risk tolerance, level of commitment, previous investments, and allocation strategies. An organized structure for investors will help the management team focus on those potential investors who are more aligned with the strategy. For instance, an investor seeking stable assets needs a different approach than an investor seeking opportunistic assets. This is critical particularly in cases where institutional investors consolidate their GP relationships in the case of real estate capital raising support.

Pitch Materials Must Demonstrate the Investment Case

However, a powerful investment presentation will go beyond simply describing attributes and returns. Investors are interested in how these returns are created. How would the business perform if the cost of capital is higher? If rental growth rates fall? What is the sensitivity of the predicted IRR to the cap rate at the exit point? How much of the value creation is based on appreciation and how much on performance? Financial models, pitch decks, market analysis, and investment memoranda must give the same answers to these questions. McKinsey stated that cap rate compression and appreciation are now riskier return drivers compared to the last cycle.

Prepare for Due Diligence Early

Institutional investors may review track records, attribution, portfolio construction, valuation approach, corporate structure, governance, service providers, reporting system, ESG policy, and cybersecurity. Managers should have all this information ready prior to commencing the actual due diligence process. Good due diligence information allows a quicker answer and prevents discrepancies among the financial model, presentation, and documentation. Effective real estate capital raising support is not just about marketing. It enables setting up the analytical foundation that will help to make an investor interested in investing.

Real Estate Capital Raising Support Strategies for Better Conversion

Although technology has the potential to increase fundraising capability, conversion requires relevance, proof, timing, and trust for real estate capital raising support. The most effective processes utilize organized investor information with personalized communication.

Real Estate Capital Raising Support

Real Estate Capital Raising Support: Precision to Close

Target Investors According to Fit

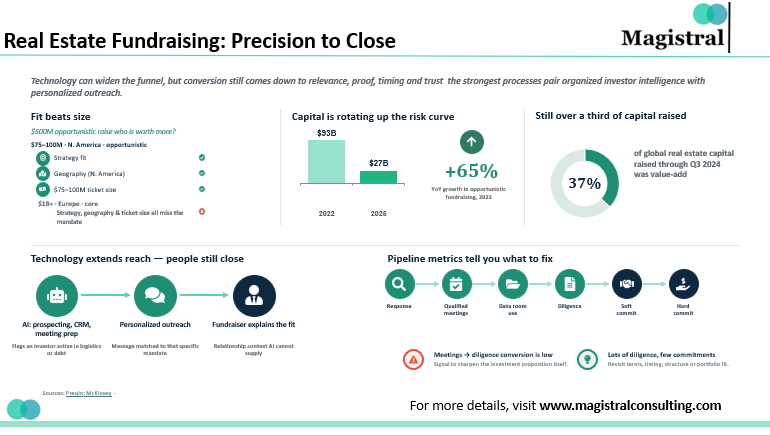
Managers can rank investors based on their property preference, geographic mandate, investment time horizon, experience of investing, return expectations, and usual ticket size. For example, when managers try to raise $500 million in an opportunistic fund, an investor who consistently invests between $75 and $100 million into North American opportunistic funds could be worth more than a large investor whose focus is European core investments. There are changes in market preferences too.

According to Preqin, value add strategies made up about 37% of total real estate capital raised through the third quarter of 2024. However, according to McKinsey, in 2025 the fundraising volume of opportunistic investments was increased by approximately 65% year over year. At the same time, fundraising volume of value add investments fell from $93 billion in 2022 to approximately $27 billion.

Use Technology With Personalization

Automated prospecting, CRM, classification of investors, preparation of meetings, and personalization of communication can be achieved via AI. Nevertheless, automation should complement relationships, not replace them. The system will be able to recognize the investor who has been investing more in logistics or real estate debt. However, the fundraising expert still needs to explain why this approach would suit that mandate. Pipeline statistics also serve as a strength.

It will help track response rate, number of qualified meetings, data room utilization, diligence process, soft commitment level, hard commitment level, and average hard commitment size. Low conversion from meetings to diligence process indicates the need for adjustments of the investment proposition. Investors who conduct extensive diligence but make few commitments suggest that fund terms, timing, structure, or portfolio need to be considered. Thus, it becomes an operationally driven process of real estate capital raising support.

How Magistral Provides Real Estate Capital Raising Support

Managers often have investment expertise but limited capacity to simultaneously conduct investor research, maintain databases, update models, prepare materials, organize data rooms, and manage outreach. External support can expand execution capacity while senior professionals concentrate on investor relationships.

Investor Research and Real Estate Capital Raising Support

Magistral Consulting’s real estate services include LP and GP outreach, HNI outreach, meeting setup, fundraising assistance, pitch deck preparation, competitive intelligence, and investment memorandum support.

Its investor database offering states coverage of more than 35,000 LP and GP leads across the United States, Europe, the United Kingdom, Middle East, India, and China. Large databases alone do not guarantee successful fundraising. Their value comes from filtering prospects according to strategy, geography, investor type, and probable fit.

Combining investor intelligence with real estate capital raising support can help managers build smaller but better qualified pipelines.

Financial Modeling and Investment Materials

Institutional investors expect the financial model, pitch deck, investment memorandum, and supporting market research to communicate the same assumptions.

Magistral’s financial modeling services cover areas such as valuation, DCF analysis, sensitivity analysis, debt analysis, comparable company analysis, and real estate financing models.

These capabilities can help managers explain return drivers and downside scenarios more clearly. They also reduce inconsistencies that may create unnecessary questions during investor diligence.

Building a Repeatable Fundraising Process

Fundraising should not restart from zero each time a manager launches a new vehicle. Investor records, market intelligence, models, reporting templates, diligence materials, and communication history can form a reusable fundraising infrastructure.

INREV reported that at least €117 billion was raised for non-listed real estate globally during 2025. Pension funds accounted for approximately 39% of capital sources, compared with 32% in 2024. Moreover, 87% of surveyed managers expected real estate capital raising support activity to increase over the following two years.

Opportunity is therefore returning, but competition remains intense. Managers can use private equity style analytical and execution support to scale research, modeling, documentation, and investor targeting without unnecessarily expanding internal teams.

Ultimately, real estate capital raising support is most effective when fundraising becomes a repeatable institutional capability. Clear strategy, defensible underwriting, targeted investor intelligence, organized diligence, and disciplined engagement allow managers to adapt as investor preferences and property markets change.


About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author

Aman is an investment-research specialist with 5+ years of experience across business and investment research, including 2+ years with Big Four firms like KPMG. A Stanford Seed alumnus with an MBA in Finance and a Bachelor of Commerce (Hons) from University of Delhi, he focuses on private equity, venture capital, and renewable energy sectors. He leads project teams at Magistral Consulting, delivering financial research, due diligence, deal sourcing, and M&A support, while driving strong process management and analytics. His blend of attention to detail, strategic thinking, and dynamic execution enables him to turn complex data into actionable investment insights.


FAQs

What does real estate capital raising support include?

It can include investor identification, LP profiling, market research, financial modeling, pitch deck preparation, investment memorandums, data room organization, outreach support, CRM management, and fundraising pipeline monitoring.

Why has raising real estate capital become more challenging?

Higher financing costs, slower distributions, valuation uncertainty, and greater investor selectivity have made fundraising more competitive. Capital has also become increasingly concentrated among larger managers.

Which investors typically allocate capital to real estate funds?

Common investors include pension funds, sovereign wealth funds, insurance companies, family offices, endowments, foundations, asset managers, funds of funds, and high net worth investors.

How can consulting improve real estate capital raising support?

Consultants can test market assumptions, analyze competitors, review operating risks, normalize financial information, model scenarios, and identify questions that materially affect valuation or the post-acquisition plan.

What Is Magistral Consulting?

Magistral Consulting is a financial-services outsourcing and research firm that supports investment banks, private equity and venture capital firms, asset managers, family offices, and corporate finance teams with analytical and operational execution.


Investor Profiling has become a practical growth tool for fund managers, founders, investment banks, and capital-raising teams. The market is no longer short of capital. It is short of well-matched capital. PwC’s 2025 Global Asset & Wealth Management Report projects global AUM to rise from US$139 trillion in 2024 to US$200 trillion by 2030, at a 6.2% CAGR. It also expects total investable wealth to exceed US$481 trillion by 2030.

In that environment, targeting, timing, and relationship intelligence matter more than broad outreach. Imagine pitching a climate infrastructure strategy to a family office that only backs late-stage software. The conversation may be polite, but it will not move. Strong investor profiling prevents that mismatch by connecting mandate, risk appetite, ticket size, geography, sector preferences, and decision-making behavior before outreach begins.

Investor Profiling and the Changing Capital Market

The process helps teams understand who is likely to invest, why they may invest, and when they are ready to engage. It turns fundraising from a volume game into a relevance game.

Investor Profiling

Investor Profiling and the Changing Capital Market

Why investor profiling now matters more

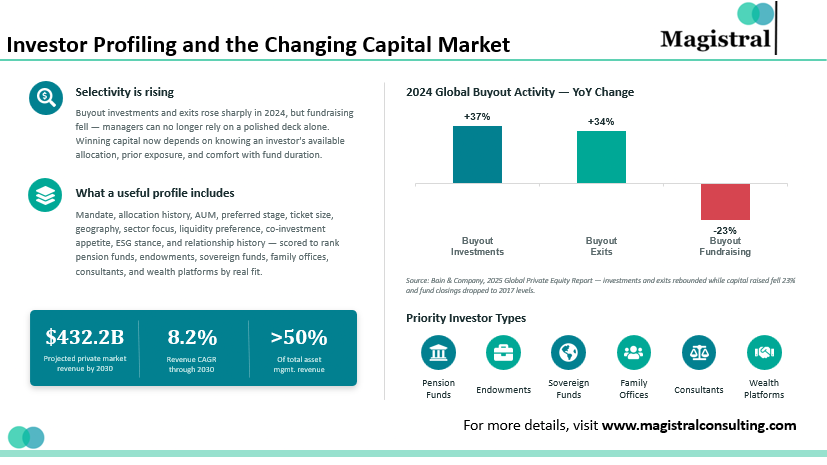
Private markets remain active, but investors have become more selective. Bain’s 2025 Global Private Equity Report noted that global buyout investments and exits rose 37% and 34%, respectively, in 2024, reversing two years of declines. Fundraising moved in the opposite direction: buyout funds raised 23% less capital globally than in 2023, and fund closings dropped to 2017 levels. In this environment, a manager cannot rely only on a polished deck. They need to know whether the target investor has available allocation, prior exposure to the asset class, and comfort with the fund’s duration.

Thoughtful investor profiling also protects senior team bandwidth. Instead of chasing every institution, teams can prioritize pension funds, endowments, sovereign funds, family offices, consultants, and wealth platforms based on real fit.

What a useful profile includes

A strong profile usually captures mandate, allocation history, assets under management, preferred investment stage, ticket size, geography, sector focus, liquidity preference, co-investment appetite, ESG stance, and relationship history. For example, an infrastructure fund may rank insurers higher if they favor long duration cash flows, while a growth equity fund may prefer family offices that already understand software scaling risk.

The role of private market growth

PwC expects private markets to become one of the most important revenue engines in asset management. Its 2025 report projects private market revenues of US$432.2 billion by 2030, growing at an 8.2% CAGR and delivering more than half of total asset management industry revenues. That growth raises the cost of weak targeting. If more managers compete for the same capital pools, a generic email feels invisible. Precise profiles make outreach feel informed.

Investor Profiling for Segmentation and Prioritization

Investor segmentation and prioritization strengthen investor profiling by ranking prospects according to fit, readiness, and strategic value. The best teams do not simply ask, “Who has capital?” They ask, “Who has the right capital for this strategy now?”

Investor Profiling

Investor Profiling for Segmentation and Prioritization

Segmentation by mandate and allocation

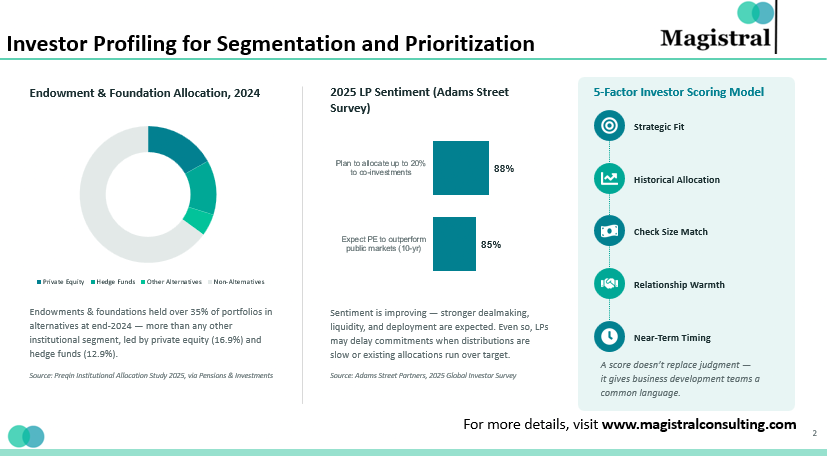
Preqin’s Institutional Allocation Study 2025 shows that investor segments behave differently across alternatives. In 2024, endowments and foundations allocated a higher percentage of AUM to alternatives than any other institutional investor segment. Pensions & Investments, citing Preqin’s study, reported that endowments and foundations had more than 35% of their portfolios in alternatives at the end of 2024, led by private equity at 16.9% and hedge funds at 12.9%. That matters because a hedge fund, secondaries vehicle, or infrastructure strategy may resonate differently with each segment.

Managers raising funds should therefore avoid one static investor list. A better approach ranks prospects by asset class exposure, recent commitments, liquidity pressure, and manager concentration.

Segmentation by stage and strategy

A venture investor that backs seed-stage fintech will not automatically fit a late-stage healthcare fund. Likewise, a buyout-focused pension mandate may not align with venture secondaries. This is where private equity and venture capital databases need qualitative review, not just keyword filters.

Practical scoring criteria

Teams can do investor profiling using five simple factors: strategic fit, historical allocation, check size match, relationship warmth, and near-term timing. A score does not replace judgment, but it gives business development teams a common language.

Prioritization by timing

Timing often separates strong prospects from polite maybes. Adams Street Partners’ 2025 Global Investor Survey reported improving sentiment in private markets, with respondents expecting stronger dealmaking, liquidity, and capital deployment. The survey also found that 85% of LPs expected private markets to deliver higher returns than public markets over the next decade, while 88% planned to allocate up to 20% of capital to co-investments. However, an investor may still delay commitment if distributions are slow or existing allocations are over target.

Investor Profiling Data, Technology, and AI Adoption

The approach now depends on clean data, enriched signals, and disciplined interpretation. AI can speed up research, but human review remains essential because capital allocation decisions are relationship-driven.

Data sources that improve accuracy

Useful inputs include regulatory filings, investment consultant notes, fund commitment databases, conference attendance, portfolio disclosures, press releases, CRM history, and public interviews. Deloitte has also highlighted alternative data as a way for investment managers to improve decision-making when used with proper governance.

For capital teams, this means a profile should not be a static spreadsheet. It should evolve as new commitments, leadership changes, allocation shifts, and market views emerge.

AI in research workflows

The global AI market was valued at about US$390.9 billion in 2025 and is projected to reach about US$3.50 trillion by 2033, according to Grand View Research. North America accounted for 35.5% of global AI revenue in 2025, while services represented the largest component share at 36.3%. This broader adoption is changing investor research as well. AI can summarize filings, flag mandate changes, cluster similar investors, and identify lookalike LPs.

Still, the final judgment should stay human. A model may identify an investor as relevant, but only an experienced analyst can judge whether the mandate truly fits the fund’s risk, liquidity, and return profile.

Why data quality matters

Bad data creates false confidence. A stale contact, outdated allocation, or wrong sector tag can waste weeks. Teams should therefore verify profile fields through at least two sources where possible. This is especially important for capital raising, where first impressions often shape the rest of the relationship.

Investor Profiling in Outreach and Relationship Management

Investor research becomes valuable only when teams use it to shape messaging, meeting preparation, and follow-up. The profile should answer a simple question before every interaction: “What matters most to this investor?”

Personalized outreach

A family office may care about founder access and co-investments. A pension fund may focus on governance, risk controls, and benchmark discipline. A wealth platform may need education, operational simplicity, and product structure clarity. When outreach reflects these differences, conversations become sharper.

Better meeting preparation

Before a meeting, teams should review the investor’s recent commitments, known consultants, prior manager relationships, investment committee cycle, and potential objections. For valuation-sensitive investors, linking strategy assumptions to DCF logic can make the discussion more credible.

Tracking relationship signals

Investor interest is rarely binary. A prospect may attend a webinar, ask for a track record, request a diligence call, then pause for six months. Strong investor profiling tracks these signals and helps teams decide when to re-engage.

How Magistral Supports Investor Profiling

Investor Profiling works best when research, analytics, and relationship context come together. Magistral supports investment teams by building investor databases, enriching profiles, mapping mandates, preparing outreach lists, and creating research-backed fundraising intelligence.

Research and database building

Magistral enables teams to find investors based on asset class, geography, sectors, ticket size, investment strategy preferences, and historical commitments. This decreases research efforts and provides fund managers with a better initial angle for engagement.

Profile enrichment and qualification

The team can enrich investor profiles by providing allocation history, recent activity, decision makers, consultant connections, and contact relevance. This helps clients separate high-priority prospects from broad market names.

Fundraising support and reporting

Magistral also supports CRM updates, meeting briefs, investor tear sheets, and market maps through its broader services. The result is a more disciplined process where every outreach decision has evidence behind it.

About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author

Tanya is an investment-research specialist with 6 + years advising venture-capital, private-equity and lending clients worldwide. A Stanford Seed alumnus with an MBA and an Economics (Hons) degree, she heads project teams at Magistral Consulting, delivering financial modelling, due-diligence and deal support on 3,000 + mandates. Her blend of rigorous analytics, sharp project management and clear client communication turns complex data into actionable investment insight.


FAQs

What is Investor Profiling?

Investor Profiling is the process of researching and categorizing investors based on mandate, allocation history, sector preference, geography, check size, risk appetite, and relationship potential

Why is Investor Profiling important for fundraising?

It helps teams focus on investors who are more likely to commit, which improves outreach efficiency, meeting quality, and capital raising outcomes

What data is used in investor profiles?

Common data includes assets under management, previous fund commitments, preferred strategies, investment stage, region, contact details, consultant relationships, and recent allocation signals

How does AI improve investor research?

AI can scan large datasets, summarize filings, identify patterns, and suggest lookalike investors, but human validation is still needed for accuracy

Who needs investor profiling support?

Fund managers, startups, investment banks, placement agents, family offices, and corporate finance teams use it to improve targeting and relationship management


Raising capital rarely comes down to having a good idea alone. It comes down to who hears about it, when they hear about it, and how the message is delivered. This is where investor reachout becomes central to a company’s or fund’s ability to close a round. A structured investor reachout helps founders and fund managers connect with limited partners, general partners, family offices, and angel investors who are genuinely suited to a deal. Done poorly, it wastes time and burns relationships before they even start. Done well, it builds a pipeline that keeps working long after the current round closes.

This article looks at the strategies that make investor reachout effective, the channels worth using, and how to measure whether the effort is paying off.

Investor Reachout

Investor Reachout: The Market Signal

Understanding the Investor Reachout Process for Fundraising Success

Investor reachout starts long before the first message goes out. It depends on knowing which investors genuinely fit the raise, and reaching them at the right moment. Getting this stage right shapes every conversation that follows.

Mapping the Right Investor Universe

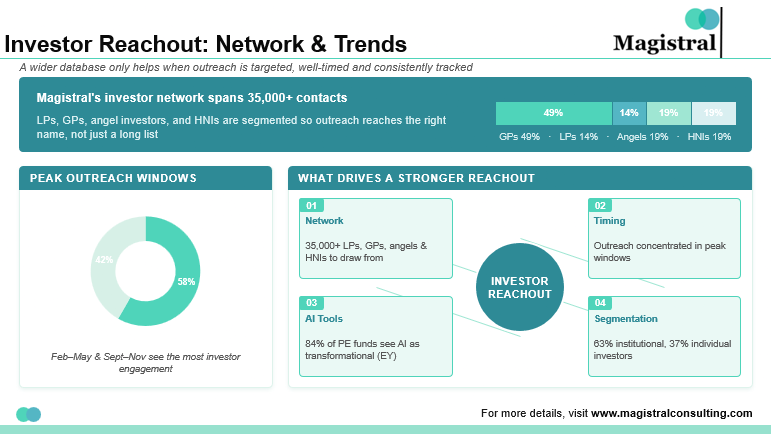
A generic contact list rarely moves a raise forward. Effective investor reachout starts with investors whose stage, sector, and cheque size match the round. Magistral Consulting’s investor database, for instance, tracks 5,000+ LPs, 17,000+ GPs, 6,500+ angel investors, and 6,500+ HNIs, which shows how granular this targeting can get.

Investor Reachout

Investor Reachout: Network & Trends

Timing the Investor Reachout

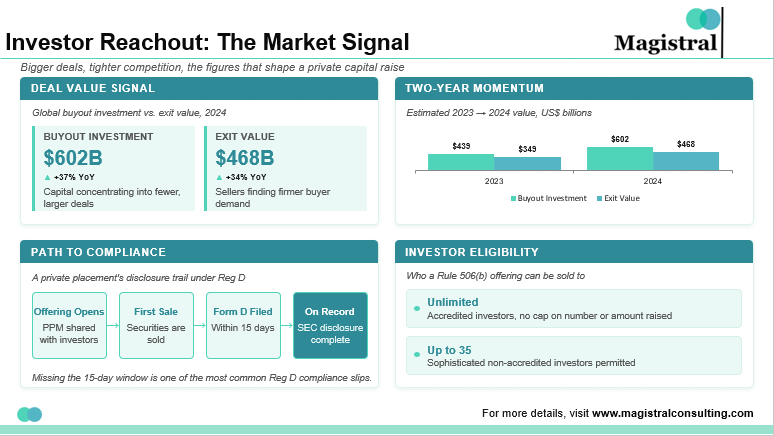
Timing matters as much as the message itself. Data suggests the ideal periods to approach investors are February to May and September to November, since these timeframes coincide with portfolio reviews, reallocation exercises, and opportunity-seeking phases. August and December, by contrast, tend to see far less investor activity.

Segmenting by Investor Type

LPs, GPs, angels, and family offices respond to different signals. A pension fund cares about governance and track record; an angel investor may respond more to founder story and market timing. Segmenting the list before drafting any message keeps the investor reachout targeted rather than generic.

Building a Clean, Verified Contact List

Stale or unverified contacts drag down response rates. A working list should include names, direct emails, LinkedIn profiles, and notes on past investments, so the reachout effort starts from accurate, current data rather than guesswork.

Crafting a Message That Gets an Investor Reachout Noticed

A strong message treats the investor as a specific person, not a line item. It anticipates objections and leads with substance rather than enthusiasm alone. A well-crafted message also respects the reader’s time, since most investors decide within seconds whether a message is worth a second look.

Personalize Every Message

Mass emails read as mass emails, and investors notice quickly. Referencing a fund’s recent investments, thesis, or portfolio overlap signals real research and improves the odds of a reply. Even a single specific line, such as a mention of a portfolio company in a related space, can separate a message from the dozens an investor skims past each week.

Lead With Evidence, Not Just Vision

Claims about market size or traction need support. If a raise cites a growing market, the message should point to the data behind it. Vague optimism rarely survives investor scrutiny; specific numbers do. Founders who anchor their pitch in unit economics, retention, or early revenue tend to earn a faster, more serious response.

Keep the First Email Short

The opening message should answer three questions fast: what the company does, why now, and what is being asked. Long introductions lose attention before the pitch even lands. A clean structure, with the ask stated plainly near the top, makes it easier for a busy investor to decide whether to engage.

Plan the Follow-Up Sequence

Most replies come after a follow-up, not the first note. A short, polite sequence spaced a week or two apart, tied to a small new update each time, keeps the conversation alive without becoming noise. Sharing a fresh milestone, a new hire, or a metric update in each touchpoint gives the investor a genuine reason to respond rather than a repeated nudge.

Choosing the Right Channels for Investor Reachout

No single channel carries a raise on its own. Combining direct outreach, warm introductions, and technology-driven tools tends to produce the strongest response rates. The right mix usually depends on the stage of the raise, the type of investor being approached, and how much of a network already exists to draw on.

Email Investor Reachout

Email remains the backbone of most investor reachout campaigns because it is direct, trackable, and easy to personalize at scale when paired with good data. It also leaves a clear record of who was contacted and when, which makes it easier to manage a large, multi-week campaign without losing track of individual conversations.

LinkedIn and Warm Introductions in Investor Reachout

A warm introduction from a mutual connection consistently outperforms a cold message. LinkedIn is often used to identify that bridge before any direct approach is made. Founders can also use it to research an investor’s recent posts or portfolio moves, which then feeds directly into a more personalized email or message.

Investor Databases and CRM Platforms for Investor Reachout

CRM-led outreach keeps track of who was contacted, when, and how they responded, which prevents duplicate or poorly timed follow-ups across a large investor list. Pairing a verified database with a CRM also makes it possible to segment investors by stage and sector, so each batch of investor reachout goes out with the right framing.

AI-Assisted Investor Reachout

AI tools now help personalize messages, monitor investor sentiment, and flag the right moment to follow up, adding real efficiency to reachout at scale. Used carefully, these tools can also draft the first pass of a message, leaving the founder or team to refine tone and add the details that make it feel genuinely personal.

Events, Conferences and Networking in Investor Reachout

In-person conversations still carry weight. Conferences and investor events often turn a cold prospect into a warm one before an email is ever sent. A short, well-prepared conversation at an event can shortcut weeks of back-and-forth once the formal reachout begins.

Measuring and Improving Investor Reachout Performance

Reachout efforts should be tracked like any other funnel. Open rates, replies, and meetings booked all tell a different part of the story, and treating the process as a funnel rather than a one-off email push makes it much easier to spot where things are going right or wrong.

Tracking Response and Meeting Conversion

Response rate shows message quality; meeting conversion shows targeting quality. Watching both separately helps pinpoint where a campaign is actually breaking down. A high response rate paired with a low meeting conversion, for example, often signals a mismatch between the pitch and the investor’s actual mandate.

Learning From Investor Feedback

Declines are still useful. Patterns in investor feedback, whether about stage, sector fit, or valuation, often point to adjustments worth making before the next batch of investor reachout goes out. Recording this feedback in a shared document, rather than letting it live in individual inboxes, helps a team spot repeated objection faster.

Avoiding Common Mistakes

Sending identical messages to every investor, ignoring timing windows, and skipping follow-ups are among the most common reasons a strong company still struggles with fundraising. Overloading the first message with too much detail, or approaching investors clearly outside the fund’s mandate, tends to waste effort on both sides.

How Magistral Consulting Supports Investor Reachout

Magistral Consulting runs this as a structured, research-driven process rather than a scattershot email push. Its team identifies and segments LPs, GPs, angels, HNIs, and family offices by geography, sector, and stage, then builds the decks, teasers, and CIMs behind the investor reachout. CRM-driven investor reachout campaigns, follow-ups, engagement tracking, and workflow automation keep the process organized end to end, while AI-assisted tools help personalize messages and time follow-ups. For founders and fund managers who want their reachout effort managed with data and discipline instead of guesswork, this kind of support can shorten the path from first contact to closed commitment.


About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author

Tanya is an investment-research specialist with 6 + years advising venture-capital, private-equity and lending clients worldwide. A Stanford Seed alumnus with an MBA and an Economics (Hons) degree, she heads project teams at Magistral Consulting, delivering financial modelling, due-diligence and deal support on 3,000 + mandates. Her blend of rigorous analytics, sharp project management and clear client communication turns complex data into actionable investment insight.


FAQs

What makes investor reachout different from a regular pitch?

A pitch is a single presentation; investor reachout is the ongoing process of identifying, contacting, and following up with the right investors before that pitch ever happens.

When is the best time to start investor reachout?

Data points to February-May and September-November as the most active windows, since these align with portfolio review and reallocation cycles.

How many investors should a reachout campaign target?

It depends on the raise, but a well-segmented list of a few hundred relevant contacts usually performs better than a broad, unfiltered list of thousands.

Does AI actually improve investor reachout results?

Used well, AI can personalize messages at scale and flag timing for follow-ups, though it works best alongside human judgment rather than replacing it.

What is the biggest mistake founders make in investor reachout?

Treating it as a one-time email blast instead of a tracked, iterative process with follow-ups and feedback built in.


Fundraising for startups represents a unique challenge and opportunity in today’s constantly shifting business landscape. With competition growing and investors becoming more sophisticated in their expectations, founders need to implement better strategies to meet capital requirements that unlock the growth stages of the company. In 2025, global venture capital funding has grown to unprecedented levels in some prominent markets, but the deal volumes are shrinking even as capital inflow into the sector has increased overall. Investor interests are narrowing as priority is given to successful quality business models over quantity. In this article, we examine the best ideas for fundraising for startups, demonstrate the benefits of operational outsourcing, and provide real industry knowledge.

Fundraising for Startups: The Evolving Landscape

There is no question that fundraising for startups has become increasingly more complex and competitive. Investors today are significantly more selective than they have been in recent years.

Fundraising for Startups: The Evolving Landscape in 2025

Fundraising for Startups: The Evolving Landscape in 2025

Key Market Trends

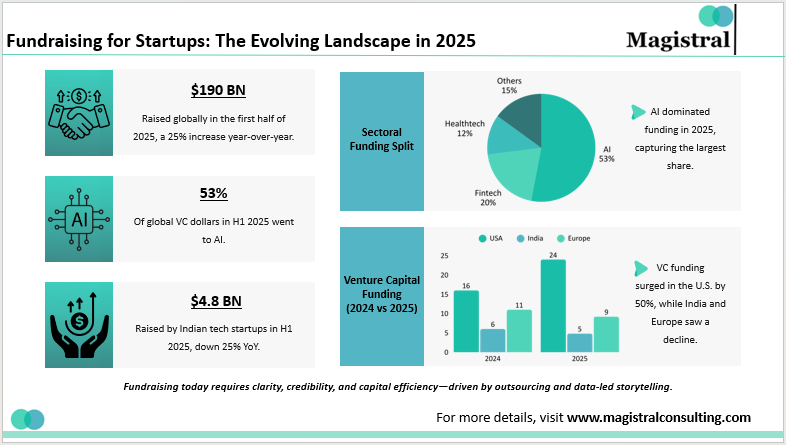
Investors want more transparency, strong unit economics, and a clear path to being profitable. Startups in fintech, AI, and health tech are accumulating most of the new funding. The average length of fundraising cycles has lengthened. Founders are pitching to more investors before completing each funding round. Outsourcing part of the fundraising process for startups is beginning to catch on to improve efficiency and results.

Data-Driven Insights

Venture capital funding exceeded 24 billion USD in the US in early 2025, representing a 50% increase from the previous year, even with fewer deals.

India’s tech startups raised USD 4.8 billion in H1 2025, ranking them third globally, with a 25% decline year-on-year.

Almost 25% of the fundraising rounds in Q1 2024 were down rounds, showing that the investor community is still interested in helping founders who are building strong fundamentals.

Investor Priorities and Market Shifts

Currently, investors expect startups to deliver data-driven stories about their business, along with a clear pathway to profitability. AI-enabled due diligence has become an established practice and has placed the onus on startups to provide more transparency, as well as quantitative metrics. The transition of funding from credit to equity has global implications, making the environment more competitive for early-stage companies.

Fundraising for Startups: Strategies for Success

To effectively fundraise for startups, you need preparation, flexibility, and targeted outreach. Startups that succeed are those that follow the playbook for investor engagement and market realities.

Laying the Foundation

Startups with product-market fit, early revenue, and an exceptional team will always catch an investor’s eye. Show traction early and demonstrate growth prospects.

Preparing Documentation

Professional pitch decks, financial models, and one-pager documents or factsheets are a “must”. Magistral Consulting has experience in all these areas and can help you produce documentation you can be proud of, that meets international standards and is meaningful to investors.

Market and Investor Research

Research into the size of your market, your competitors, and your investors’ interests allows you to position yourself appropriately. If you know your audience, you can be more targeted in your outreach.

Building Relationships

Making contact early on with potential investors and mentors can lead to introductions and help. Relationships run deep in the investment community. Putting effort into relationship building with investors will pay off during funding rounds when you are asking for money.

Operational Readiness

Startups should organize relevant legal, financial, and operational structure documentation before they start approaching investors for support. This would lend credibility and aid the due diligence process.

Diversifying Funding Sources

Combining traditional and innovative funding methods can provide resilience and flexibility.

Angel Investors and Venture Capital

Focusing on investors with direct experience in your sector will improve your odds of success. These investors usually come with capital and have valuable industry insights.

Crowdfunding and Revenue-Based Financing

Flexibility and less dilution are the most appealing aspects of these alternative funding models. Crowdfunding platforms and revenue-based funding provide mechanisms for capital without the loss of ownership or a huge equity stake.

Strategic Partnerships

Working with established companies can bring both capital and access to the market. Other contributions can include distribution and operational functions.

Leveraging Outsourcing in Fundraising for Startups

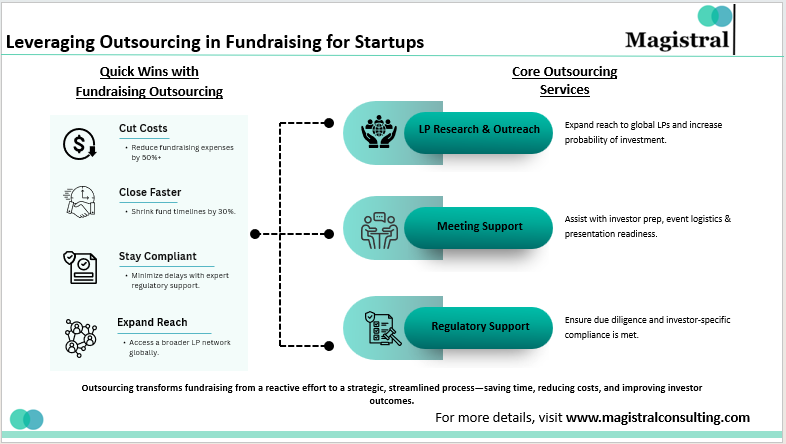
If a startup can outsource parts of the fundraising process, we can improve speed and overall results for the startup. Throughout this process, Magistral Consulting has handled fundraising for startups and for funds from the very beginning – documentation through investor outreach.

Leveraging Outsourcing in Fundraising for Startups

Leveraging Outsourcing in Fundraising for Startups

LP Research and Outreach

Magistral profiles and reaches out to Limited Partners (LPs) worldwide for our clients and expands the number of potential investors. This systematic and intentional approach enhances the probability of gaining investment from LPs.

Meeting & Event Support

When joining the fundraising process, we also helped with the unsexy items, such as preparing for meetings with investors and industry conferences. This full cycle support undoubtedly increases preparedness for founders and increases the chances of making a positive impression on a potential LP investor. There are multiple items we help with, including logistics, presentation preparation, and overall follow-up.

Costs and Efficiency Benefits

Outsourcing parts of the fundraising journey can lead to cost savings upwards of 50%, as well as a reduction in overall fund-close timelines of upwards of 30%1. This means startups can use their time savings to devote more resources to product development and expanding the market for their services.

Regulatory and Compliance Guidance

There are lots of regulatory and compliance aspects to consider while fundraising. Thankfully, the specialists we find help manage these regulatory challenges, and due diligence steps reduce each startup’s risk. In addition, compliance support can ensure that the potential startup has met the requirements of the potential investor. This can prevent delays and costs associated with not being compliant.

Trends Shaping Fundraising for Startups in 2025

Founders must adapt to emerging trends to remain competitive. The rules of the fundraising game are evolving due to new technologies, investor behaviors, and shifts in worldwide markets.

AI and Digital Transformation

Artificial Intelligence is redefining due diligence and deal sourcing while making data-driven storytelling a must. AI tools can help founders analyze market trends and better understand the wants, needs, and behaviors of investors.

Rise of Micro-VCs and Syndicates

Smaller funds are investing in niche markets and pre-stage companies while providing guidance AND capital. Micro-VCs are also typically nimbler and can act on an investment decision quicker than other funds.

Global Shifts in Funding

While the US dominates the venture capital landscape, India and Japan are still managing to weather the storm. China, however, has seen double-digit downturns in both deal volume and deal value, which may highlight some of the shifted patterns in global funding.

Sector Focus

Startup companies in sectors like AI, fintech, and Health tech are raising larger rounds of funding that indicate the interests of investors who are hungry to support innovation. In these sectors, startup companies should be promoting their technological advantages and scalability.

Outsourcing as a Strategic Advantage

While founders use outsourcing to enhance fundraising, they also gain access to tailored expertise, scalable solutions, and global investor networks. This allows founders to concentrate on business growth.

About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author

The article is authored by the Marketing Department of Magistral Consulting. For any business inquiries, you can reach out to prabhash.choudhary@magistralconsulting.com

[sp_easyaccordion id=”4137″]