Tag Archives: financial data management

Financial Process Outsourcing is becoming a strategic finance solution as organisations face rising reporting demands, regulatory complexity, talent shortages, and rapid AI adoption. This article examines the market’s growth, key adoption drivers, regional shifts, investment activity, and emerging opportunities shaping the FPO landscape in 2026 and beyond.

Why Financial Process Outsourcing Is Scaling Fast in 2026

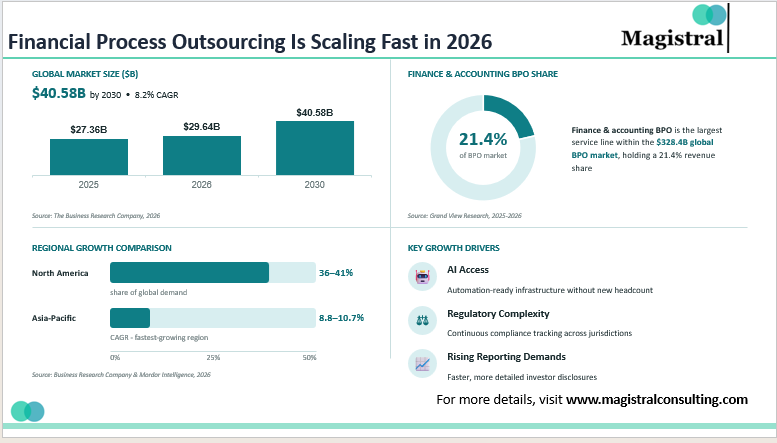
Financial Process Outsourcing is shifting from a cost-saving tactic to a core finance strategy worldwide. The global market reached $29.64B in 2026, up from $27.36B in 2025, growing at an 8.3% CAGR, and is expected to approach $40.58B by 2030. Growth is increasingly driven by AI access, regulatory complexity, and rising reporting demands. Alternative investment managers are outsourcing fund accounting, NAV calculation, and investor reporting to build institutional-grade infrastructure without adding permanent headcount.
Financial Process Outsourcing

Financial Process Outsourcing Is Scaling Fast in 2026

Financial Process Outsourcing Market Size and Growth Outlook

The financial process outsourcing market has moved past early-stage niche status into a multi-billion-dollar global category. Independent research houses differ on exact figures, but every major estimate points towards consistent, high-single-digit growth through the end of the decade.

Global Market Valuation and Compound Growth

The Business Research Company sizes the market at $29.64B in 2026, up 8.3% from $27.36B in 2025. The market is projected to grow at an 8.2% CAGR through 2030, reaching $40.58B. This growth signals structural rather than cyclical demand.

Finance and Accounting BPO as the Anchor Segment

Grand View Research values finance and accounting BPO at $70.2B in 2025, rising to $76.5B in 2026, with a 9.3% CAGR through 2033. Within the $328.4B global BPO market, it is the largest service line, holding a 21.4% revenue share.

Regional Growth Differentials

North America holds the largest share of financial process outsourcing, at 36%–41% of global demand. Asia-Pacific is growing fastest, with CAGRs of 8.8%–10.7%, as regional enterprises adopt outsourcing more aggressively.

Forecast Through 2030 and Beyond

Beyond the $40.58 billion 2030 estimate, Mordor Intelligence projects the wider finance and accounting outsourcing category reaching $85.92 billion by 2031. The spread reflects differing scope definitions, but the direction is unambiguous: the sector is compounding faster than professional services at large.

Key Drivers Behind Financial Process Outsourcing Adoption

AI adoption, mounting regulatory complexity, and thinly staffed internal finance teams are pushing more organisations towards providers that can supply both delivery scale and specialised technology.

AI and Automation Inside Finance Functions

Deloitte’s Q4 2025 CFO Signals survey found that 87% of CFOs expect AI to be extremely or very important to finance operations in 2026, while 63% of finance departments already use AI. 81% are adopting AI through outsourced providers, as specialised AI talent remains scarce internally.

Rising Regulatory and Reporting Complexity

The EU Corporate Sustainability Reporting Directive requires disclosure of ~1,100 data points across 50,000+ entities from 2026. With limited internal capacity, finance teams are increasingly relying on providers for compliance-adjacent services.

Rising Regulatory and Reporting Complexity

Forecasts for 2026–2030 highlight rising adoption among small and mid-sized enterprises, driven by cloud-based finance platforms. Lower entry costs are making outsourced finance accessible beyond large enterprises to leaner organisations.

Rising Regulatory and Reporting Complexity

Lean finance teams often face capacity gaps as fund structures become more complex. Side letters, waterfalls, and multi-currency vehicles are driving greater use of outsourced NAV calculation and financial process outsourcing to meet investor expectations.

Geographic Shifts Reshaping Financial Process Outsourcing Delivery

Delivery is consolidating around a small number of global hubs, with India extending its lead as capability centres move from transactional processing towards strategic ownership.
Financial Process Outsourcing

Geographic Shifts Reshaping FPO Delivery

India’s Expanding Global Capability Centre Footprint

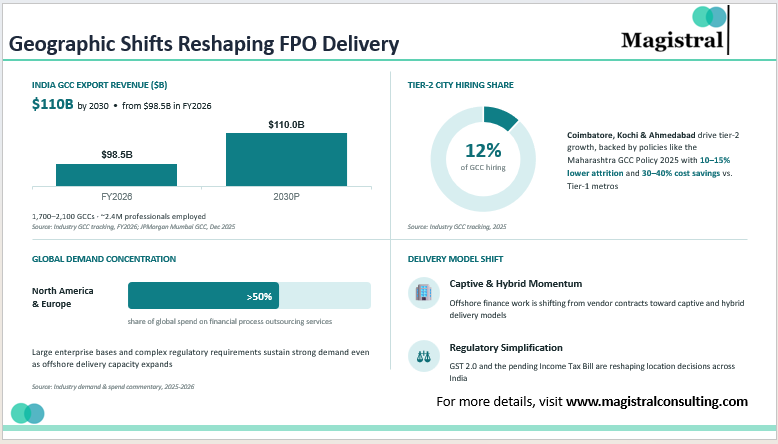
Industry tracking counts 1,700–2,100 GCCs in India, employing ~2.4M professionals and generating ~$98.5B in FY2026 exports, projected to reach $110B by 2030. JPMorgan Chase’s December 2025 plans for Asia’s largest GCC in Mumbai highlights India’s shift towards strategic infrastructure, beyond cost-driven back offices.

Tier-2 City Expansion

Coimbatore, Kochi, and Ahmedabad account for ~12% of GCC hiring, supported by policies like the Maharashtra GCC Policy 2025. Attrition is 10%–15% lower than Tier-1 metros, with 30%–40% talent-cost savings.

North America and Europe as Demand Centres

North America and Europe account for well over half of global spend on these services. Their large enterprise bases and complex regulatory requirements sustain strong demand. This remains true even as offshore delivery capacity expands.

Captive GCCs Versus Third-Party Vendors

Offshore finance work is shifting from vendor contracts to captive and hybrid models.
India’s regulatory simplification is supporting this transition.
GST 2.0 and the pending Income Tax Bill are influencing location decisions.

Investment and Deal Activity in Financial Process Outsourcing

Private capital is consolidating financial process outsourcing providers, favouring scale and AI-enabled delivery capability over simple headcount growth.

Private Equity Appetite for Services Platforms

Global M&A value reached $4.9T in 2025, up 37% YoY, with private-equity-backed transactions totaling ~$1.8T. This capital is increasingly flowing into business services and technology-enabled platforms. Finance and accounting providers with recurring revenue are benefiting from this trend.

Platform Buyouts and Scale as a Deal Thesis

PitchBook expects platform buyouts to reach at least 25% of private equity deals in 2026, with larger funds gaining share. In FPO, sponsors are consolidating smaller providers into scalable platforms to support AI investment and cross-selling.

Strategic Reviews Among Established Providers

Consolidation pressure is visible across established BPO players. Conduent explored a potential sale in early 2025 after attracting takeover interest, signalling continued strategic repositioning across the broader sector.

Emerging Opportunities and the Road Ahead for Financial Process Outsourcing

The next phase will be defined by ESG reporting demand, agentic AI, and closer integration with fund operations for alternative asset managers.

ESG and Sustainability Reporting Services

Providers are expanding financial close services into materiality assessment and carbon-footprint tracking as disclosure requirements grow. This turns compliance needs into a new outsourced service opportunity.

Agentic AI and Touchless Finance Operations

Providers are moving from AI copilots to agentic systems that automate complex finance workflows with limited human oversight. Deloitte is already applying these capabilities to tasks such as month-end close and vendor validation.

Institutional-Grade Reporting for Alternative Managers

Alternative investment managers are among the fastest adopters as reporting complexity outpaces internal capacity. Private credit, real estate, and venture funds increasingly use outsourced NAV calculation, fund administration, accounting, and financial modelling to deliver institutional-quality reporting without expanding permanent staff.

What This Means for CFOs and COOs

Financial process outsourcing is becoming a strategic infrastructure choice, enabling faster scaling, regulatory readiness, and AI adoption. Firms treating finance functions as core infrastructure can better compete for capital and talent.

Services Offered by Magistral Consulting for Financial Process Outsourcing

General Ledger & Accounting

End-to-end management of accounting activities, reconciliations, journal entries, and financial close processes to ensure accurate and timely books.

Financial Reporting & MIS

Preparation of financial reports, dashboards, and MIS to deliver clear, timely, and actionable insights for management.

Financial Planning & Analysis (FP&A)

Budgeting, forecasting, financial modelling, and variance analysis to support strategic planning and informed business decisions.

Cash Flow & Treasury Management

Cash-flow forecasting, liquidity monitoring, payment management, and treasury support to optimise working capital and cash utilisation.

Payroll & Expense Processing

Accurate processing of payroll, employee expenses, reimbursements, and related financial reconciliations while maintaining compliance.

Tax & Compliance Support

Preparation of financial data, tax reports, compliance documentation, and regulatory requirements to minimize financial and compliance risks.

Financial Data Management & Analytics

Collection, validation, analysis, and reporting of financial data to improve data quality, visibility, and decision-making.

Financial Controls & Quality Assurance

Implementation of financial controls, validation processes, and quality checks to enhance accuracy, consistency, and governance.


About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author
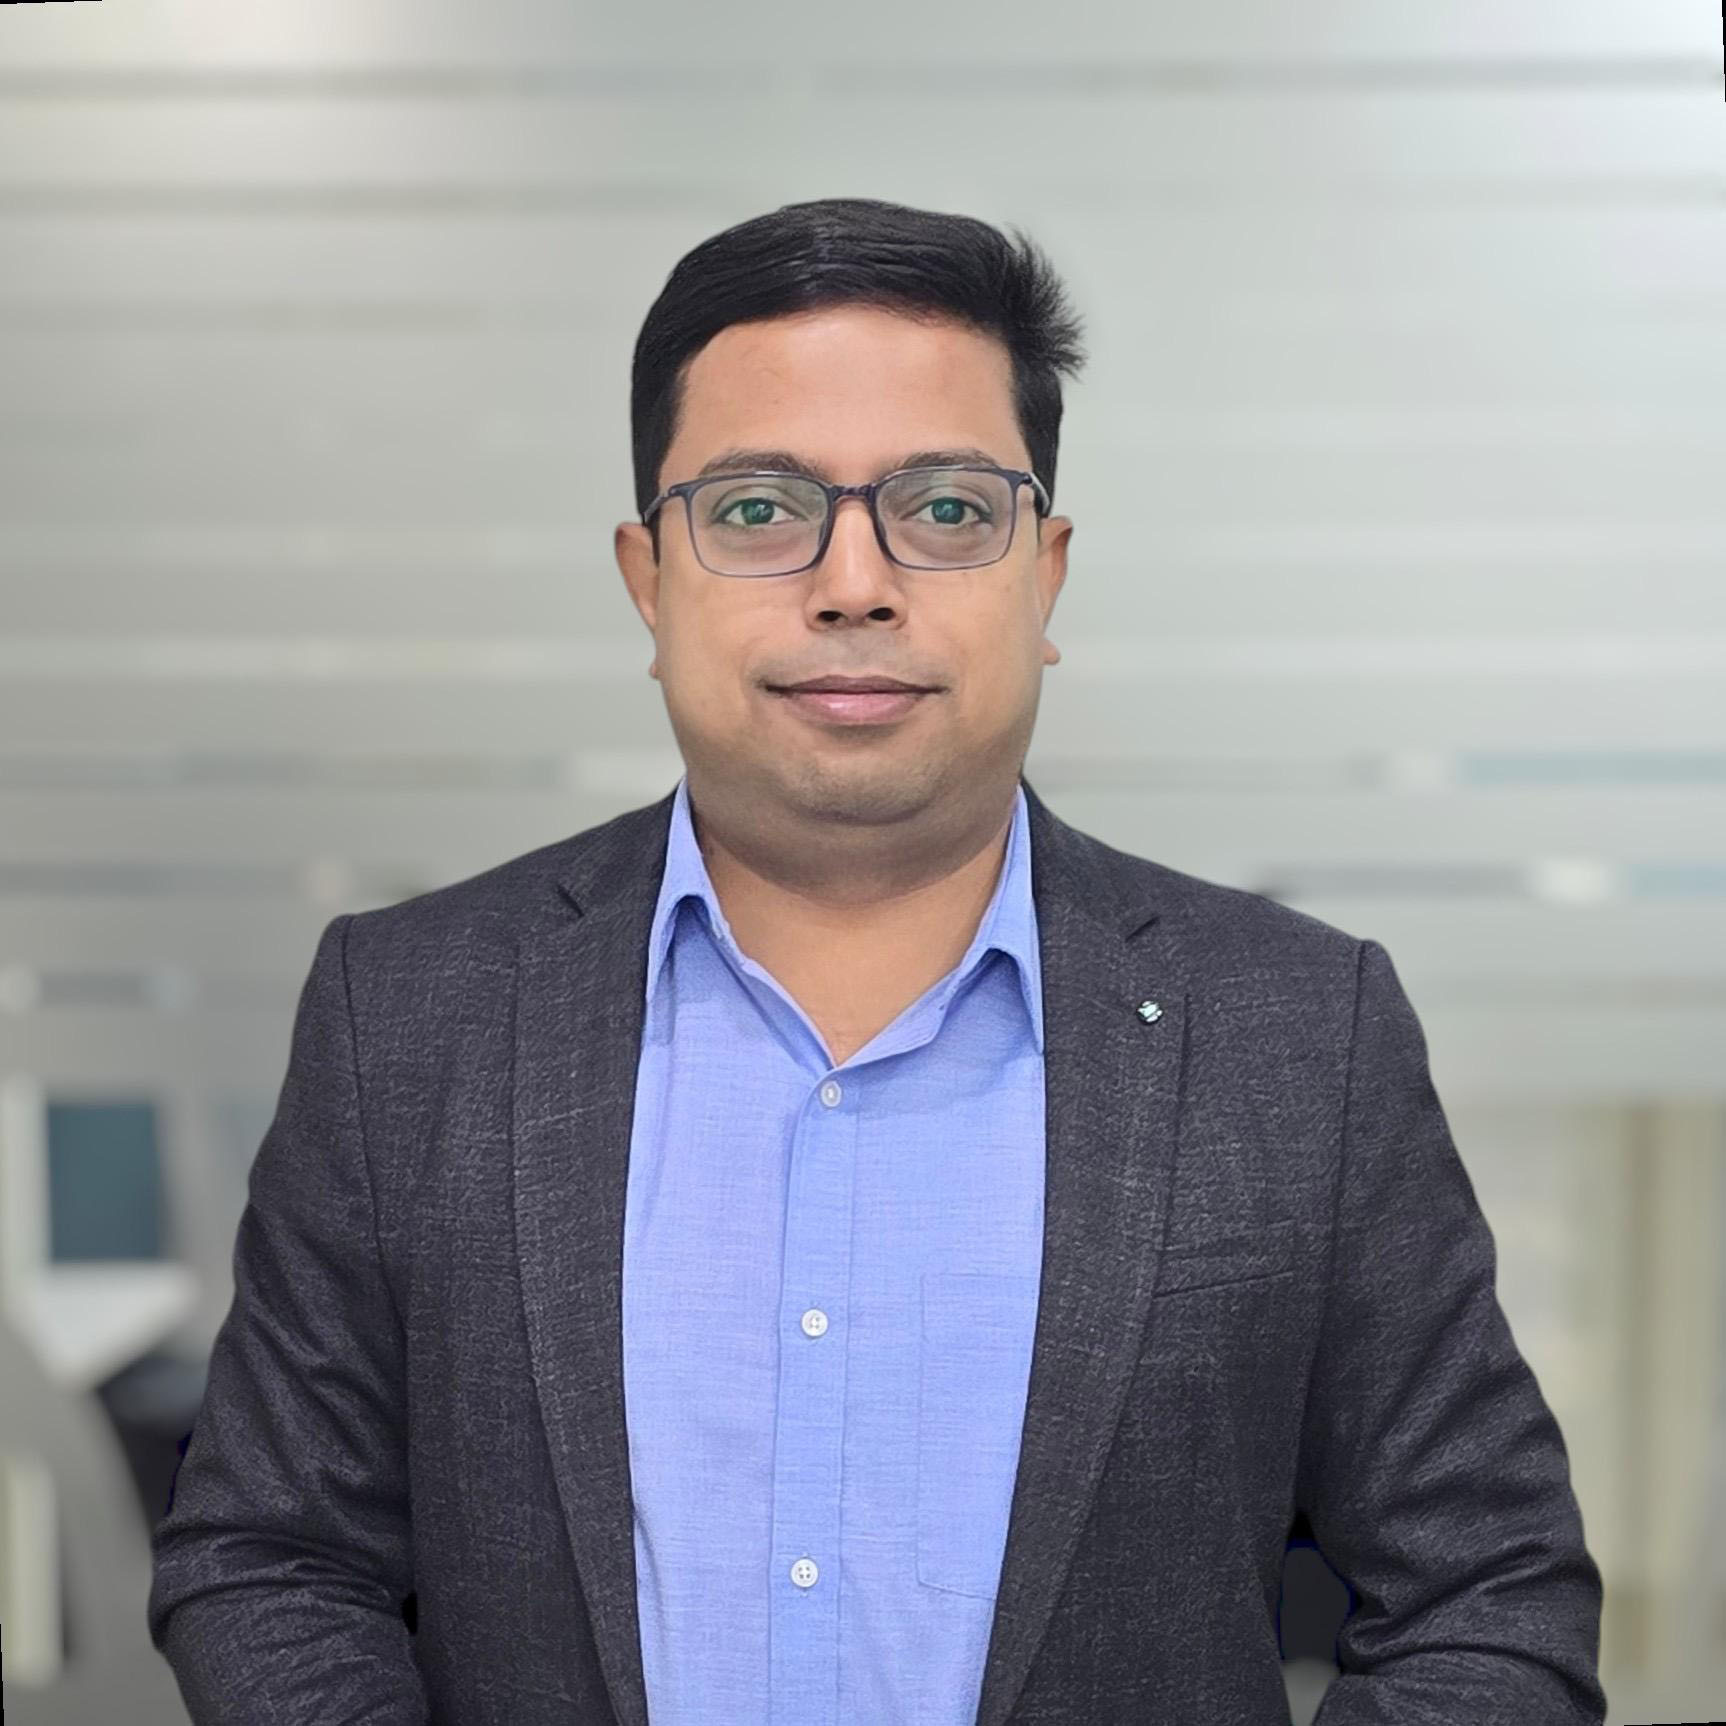
Nitin is a Partner and Co-Founder at Magistral Consulting. He is a Stanford Seed MBA (Marketing) and electronics engineer with 19 + years at S&P Global and Evalueserve, leading research, analytics, and inside‑sales teams. An investment‑ and financial‑research specialist, he has delivered due‑diligence, fund‑administration, and market‑entry projects for clients worldwide. He now shapes Magistral Consulting’s strategic direction, oversees global operations, and drives business‑development support.


FAQs

What is financial process outsourcing?

Delegating finance and accounting functions such as bookkeeping, reconciliations, NAV calculation, and reporting to external specialists.

How large is the financial process outsourcing market in 2026?

The market is $29.64 billion in 2026, growing at 8.3% CAGR and projected to reach ~$40.58 billion by 2030, according to The Business Research Company.

Which regions lead financial process outsourcing delivery?

North America leads consumption at 36%–41% of global demand, while India leads delivery capacity and Asia-Pacific is the fastest-growing consumption region.

How is AI changing financial process outsourcing?

AI is shifting delivery towards automated workflows, with ~81% of finance functions adopting AI through outsourced providers.

Which functions benefit most from financial process outsourcing?

Fund accounting, NAV calculation, investor reporting, financial modelling, and compliance reporting, especially among alternative asset managers.


Introduction

In the vast domain of finance, credit research emerges as a foundational element for evaluating and managing credit risk. It serves as a vital instrument for informed decision-making in lending, investing, and risk mitigation. Credit research entails thoroughly examining the creditworthiness of borrowers or issuers, aiming to gauge the likelihood of default and associated risks associated with extending credit or investing in debt instruments.

Understanding Credit Research

Credit research employs a holistic approach, melding qualitative and quantitative analyses to assess the creditworthiness of entities. Qualitative factors delve into various dimensions such as industry dynamics, management caliber, competitive positioning, and regulatory backdrop. Conversely, quantitative analysis entails the evaluation of financial metrics like leverage ratios, liquidity ratios, cash flow generation, and debt service coverage.

The Role of Credit Analysts

Credit analysts assume a pivotal role in conducting credit research. These professionals meticulously analyze financial statements, delve into industry research, and scrutinize macroeconomic factors to construct a comprehensive perspective of credit risk. They harness an array of tools and methodologies, including financial modeling, scenario analysis, and stress testing, to ascertain creditworthiness accurately.

Key Components of Credit Research

The key components of credit research encompass various aspects essential for evaluating the creditworthiness of borrowers or issuers and managing credit risk effectively. These components include:

Key component of credit research

Key component of credit research

Industry Analysis

Understanding industry dynamics and trends holds paramount importance in assessing credit risk. Factors such as market competition, regulatory climate, technological advancements, and macroeconomic conditions significantly influence credit risk. Delving deep into industry specifics and staying abreast of emerging trends enables a comprehensive evaluation of creditworthiness. It aids in the identification of potential risks and opportunities within the sector.

Financial Analysis

A meticulous scrutiny of the borrower’s financial statements furnishes insights into its financial robustness and stability. Crucial financial metrics such as revenue growth, profitability, leverage, liquidity, and cash flow generation are subject to analysis. In-depth financial analysis goes beyond surface-level examination, uncovering underlying patterns and anomalies that may impact creditworthiness, thereby facilitating informed decision-making and risk mitigation strategies.

Management Evaluation

Evaluating the quality and proficiency of the management team assumes paramount significance in credit research. A proficient and seasoned management cadre can adeptly navigate operational risks and surmount challenges posed by dynamic business environments. Assessing management competence involves scrutinizing leadership qualities, strategic vision, and past performance, offering valuable insights into the organization’s ability to navigate uncertainties and uphold financial commitments.

Financial Reliability

Gauging the borrower’s capacity and willingness to honor its debt obligations forms the bedrock of credit research. Factors such as credit history, repayment track record, collateral, and overall financial stability are accorded meticulous consideration. A comprehensive assessment of creditworthiness involves evaluating both quantitative metrics and qualitative factors, ensuring a nuanced understanding of the borrower’s financial health and repayment capabilities.

Market Analysis

Vigilant monitoring of market conditions and trends is imperative to grasp the broader economic canvas and its implications on credit risk. Variables such as interest rates, inflation, currency dynamics, and geopolitical developments exert a profound influence on creditworthiness. By staying attuned to market fluctuations and anticipating shifts in economic indicators, credit analysts can proactively identify emerging risks and opportunities, enabling timely adjustments to credit strategies and risk management frameworks.

Methods of Credit Research

Bottom-Up Approach

This method involves meticulously examining individual securities or borrowers, focusing on their unique characteristics and financial metrics. By concentrating on micro-level factors that influence credit risk, analysts gain a granular understanding of the inherent risks associated with each entity. This approach enables a detailed assessment of factors such as revenue streams, expense structures, asset quality, and cash flow patterns. By delving deep into the specifics of each security or borrower, analysts can identify potential vulnerabilities and opportunities that may not be apparent at a macroeconomic level.

Top-Down Approach

On the other hand, the top-down strategy takes a more comprehensive stance, starting with an examination of general market and economic patterns. To assess the overall state of the economy, analysts look at macroeconomic indices including GDP growth, inflation rates, interest rates, and geopolitical developments. This macro-level analysis offers a framework for comprehending how external influences may affect credit risk in different industries and sectors. A more thorough risk assessment is made possible by analysts’ ability to recognize systemic risks and trends that could concurrently impact several industries or borrowers by beginning with a top-down perspective.

Comparative Analysis

Comparative analysis compares the credit histories of issuers or borrowers that are comparable within the same sector or industry. Analysts can determine the relative strengths and weaknesses of comparable companies by looking at their credit histories, risk considerations, and important financial data. This comparison method enables a more sophisticated risk assessment and offers insightful information about the relative creditworthiness of various companies. Analysts might find opportunities or dangers that may have gone unnoticed by benchmarking against peers to find outliers and abnormalities.

Scenario Analysis

Scenario analysis entails evaluating the potential impact of various macroeconomic or industry-specific scenarios on a borrower’s ability to meet its debt obligations. Analysts develop a range of hypothetical scenarios, such as economic downturns, industry disruptions, or geopolitical crises, and assess the potential outcomes for each scenario. This forward-looking approach helps to identify potential vulnerabilities and sensitivities within a borrower’s financial structure. By stress-testing against a range of scenarios, analysts can assess the resilience of a borrower’s credit profile and develop contingency plans to mitigate potential risks.

The 5Cs of Credit Research

Lenders and investors utilize the core concepts known as the 5Cs of credit research to evaluate borrowers’ creditworthiness. These elements offer a methodical framework for assessing the risk involved in giving credit or making investments in debt instruments.

The 5 C's of Credit research

The 5 C’s of Credit research

Character

Character is a term that describes a borrower’s standing, morality, and willingness to pay back loans. Lenders evaluate the borrower’s credit history, taking into account the borrower’s payment history on time, past debt management experience, and any defaults. Lenders are reassured by a strong credit history, which shows dependability and fiscal discipline. To further assess the borrower’s character, background checks and personal references could be consulted.

Capacity

Capacity evaluates the borrower’s ability to repay the debt based on their income, cash flow, and financial obligations. Lenders analyze factors such as income stability, employment status, and debt-to-income ratio to assess the borrower’s capacity to meet future payment obligations. A stable income stream and manageable debt burden indicate a higher capacity to repay, reducing the risk of default.

Capital

Capital refers to the borrower’s financial reserves, assets, and investments that can serve as collateral or provide a cushion in case of financial difficulties. Lenders consider the borrower’s equity position, net worth, and liquidity of assets when evaluating capital. Adequate capital demonstrates the borrower’s financial strength and ability to absorb losses, reducing the lender’s risk exposure.

Collateral

Collateral is anything material that the borrower pledges as security for the loan. It gives the lender some protection in the event of default by giving them a way to recoup losses. Typical collateral kinds include merchandise, cars, real estate, and accounts receivable. Collateral is evaluated for quality and value in order to determine how effective it is at reducing credit risk. To reduce the risk of lending to applicants with less favorable credit histories, lenders might demand collateral.

Conditions

Conditions include outside variables including the state of the economy, business trends, and regulatory framework that could affect the borrower’s capacity to repay the debt. To determine the total risk exposure, lenders consider the loan’s intended use, the state of the market, and the borrower’s industry prospects. Interest rates, inflation, and geopolitical threats are among the other factors taken into account. Lenders can foresee possible hazards and modify lending requirements by having a thorough understanding of the current situation.

Magistral’s Credit Research Services

At Magistral Consulting, we understand the intricate dynamics and specific challenges faced by B2B enterprises and CPA firms. Our credit research services are meticulously designed to address these challenges. We also provide actionable insights that drive business growth and profitability.

Industry-Specific Analysis

We conduct in-depth industry analysis tailored to the specific sectors in which B2B enterprises and CPA firms operate. By understanding sector-specific trends, regulatory environments, and competitive landscapes, we provide valuable insights into industry dynamics that impact credit risk.

Financial Performance Evaluation

Our team of seasoned analysts performs thorough financial performance evaluations, focusing on key metrics relevant to B2B and CPA companies. From revenue growth and profitability to leverage ratios and cash flow generation, we provide a comprehensive assessment of financial health and stability.

Client Risk Assessment

Magistral Consulting excels in client risk assessment, evaluating the creditworthiness of counterparties and clients with precision. By analyzing credit histories, payment behaviors, and collateral, we provide actionable recommendations to mitigate risk exposure and safeguard against potential defaults.

Macro-economic Analysis

We integrate macroeconomic analysis into our credit research services, keeping our clients abreast of broader economic trends and market conditions. From interest rate fluctuations to geopolitical risks, we provide insights into external factors that may impact credit risk for B2B enterprises and CPA firms.

Customized Solutions

Since every customer is different, we provide specialized credit research solutions made to meet the demands of CPA firms. We offer specialized solutions that produce noticeable outcomes. Whether the goal is creating risk management frameworks, finding growth prospects, or optimizing credit policies, we provide customized solutions to address all challenges.

About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author

The article is Authored by the Marketing Department of Magistral Consulting. For any business inquiries, you could reach out to prabhash.choudhary@magistralconsulting.com