Tag Archives: credit underwriting

Investment banking capital-markets activity improved in the first half of 2026, although the recovery remained unusually concentrated. LSEG reported that the total value of global M&A transactions reached a record US$2.85 trillion in the first half of 2026, while transaction volume fell to a six-year low. In the United States, PwC reported that M&A value reached US$1.2 trillion in the first five months of the year, nearly double the comparable 2025 figure, even as transaction volume declined 4%. These patterns have changed the approach to underwriting in investment banking.

Larger transactions, complex financing structures, volatile interest rates, and divergent sector expectations require underwriting teams to assess not only whether a transaction is viable under a base case, but also how quickly its economics deteriorate when interest expense, revenue expectations, working-capital, or exit assumptions move against the investment thesis. As a result, underwriting now places greater emphasis on scenario analysis, downside protection, information quality, and transaction structure.

The 2026 Underwriting in Investment Banking Environment: More Capital, Greater Selectivity

High deal values are apparent from headlines; underwriting conditions are still tough underneath. Regional variation also means underwriting in investment banking must reflect local liquidity, regulation, and investor demand.
Underwriting in Investment Banking

The 2026 Underwriting in Investment Banking Environment: More Capital, Greater Selectivity

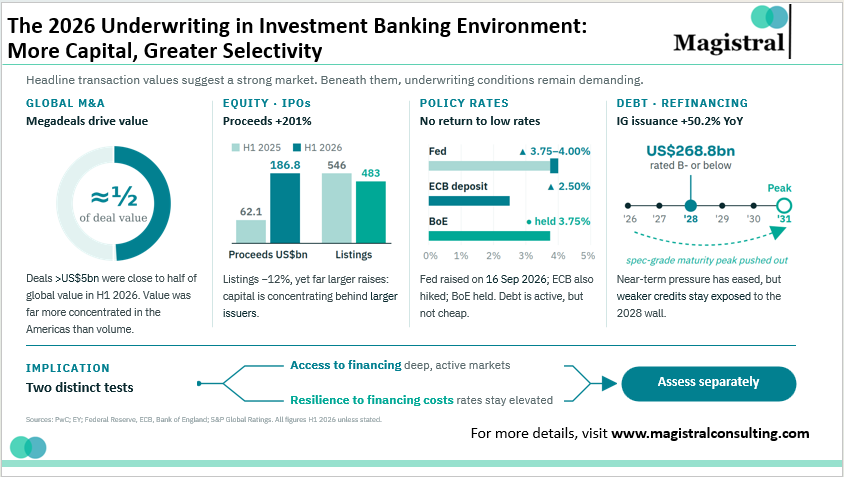
An example from global M&A provides evidence of this dichotomy. Deals valued above US$5 billion accounted for nearly half of the global deal value in the first half of 2026, as revealed by PwC. The deal value was much more concentrated in the Americas region compared to the number of deals there.

The equity issuance activity is robust, too. As reported by EY, there were 483 global IPOs generating US$186.8 billion of proceeds in H1 2026, compared to 546 IPOs raising US$62.1 billion in H1 2025, a 201% increase despite a 12% reduction in the number of IPOs.

Debt markets are active, but funding costs have not returned to the low levels of the previous decade. On September 16, 2026, the Federal Reserve raised the target range for the federal funds rate to 3.75%–4.00%. The European Central Bank raised its deposit facility rate to 2.50%, effective September 16, while the Bank of England maintained the bank rate at 3.75% at its September meeting. These decisions reinforce the need to evaluate transaction economics under a range of financing-cost scenarios. Targeted external support can strengthen underwriting in investment banking by expanding analytical capacity during peak workloads.

Nevertheless, refinancing activity has been substantial. According to S&P Global Ratings, nonfinancial investment-grade issuance increased 50.2% from the first half of 2025, pushing the peak maturity year for speculative-grade bonds to 2031. Although near-term refinancing pressure has eased for most borrowers, weaker credits remain vulnerable; S&P identified US$268.8 billion of debt rated B− or lower that matures in 2028.

The underwriting implication is clear: financing availability and refinancing risk must be evaluated separately.

These pressures make underwriting in investment banking more demanding when information is incomplete, or market conditions shift quickly.

Underwriting in Investment Banking: How Assumptions Are Changing

A traditional base case model is not sufficient to evaluate transactions in 2026.

Downside scenarios are receiving greater weight. Revenue growth, margin assumptions, and valuation multiples need to be analyzed together rather than individually. A company that appears appropriately leveraged under management’s estimates may look substantially different if revenue growth slows and elevated financing costs persist.

Debt-service capability is receiving a more stringent test. Floating rate exposure, a refinancing schedule, and covenant cushion join leverage as key underwriting factors. Underwriting evaluation increasingly focuses on interest coverage, fixed charge coverage, free cash-flow yield, and liquidity in various capital structures.

Earnings quality is becoming more important than the headline EBITDA figure. S&P Global Ratings’ review of U.S. speculative-grade issuers found that EBITDA add-backs represented approximately 30% of market-adjusted EBITDA across a decade of data. This finding underscores the importance of validating adjustments, projected synergies, and management-defined earnings measures.

Cash-flow sustainability is also receiving greater emphasis. Working-capital seasonality, customer concentration, recurring versus project-driven revenue, capital-expenditure requirements, and contractual revenue recognition all affect whether accounting earnings support debt service.

Sponsor-led deals add another dimension to underwriting. In addition to operating performance, underwriters must assess the equity contribution, shareholder support, dividend capacity, and refinancing or exit potential. A deal that depends on multiple expansions or early refinancing has a substantially different risk profile from one that reduces debt through cash flow. As a result, underwriting in investment banking benefits from consistent data, transparent models, and clear escalation paths.

Regional Underwriting in Investment Banking

Regional underwriting approaches vary considerably across markets, reflecting differences in deal activity, financing conditions, regulatory frameworks, and investor appetite.
Underwriting in Investment Banking

Regional Underwriting in Investment Banking

North America

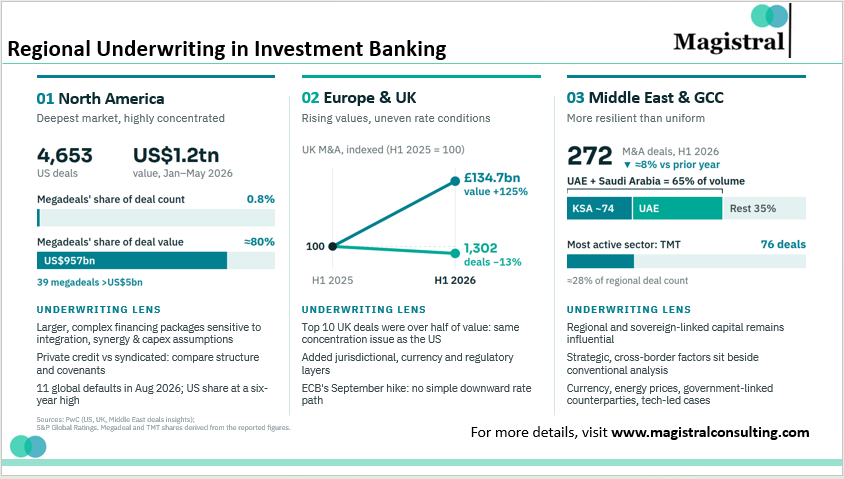
North America continues to have the deepest transaction and financing markets, although activity is highly concentrated. According to PwC, 4,653 U.S. deals worth US$1.2 trillion were announced in the first five months of 2026. Of these, 39 transactions were valued at more than US$5 billion, and those megadeals represented US$957 billion of total value.

From a financing perspective, larger transactions are more difficult to finance and are especially sensitive to assumptions about integration, synergies, and future capital requirements. The availability of both private credit and broadly syndicated financing also makes comparisons of structures and covenants increasingly important.

Credit deterioration has not disappeared. S&P Global Ratings reported 11 global corporate defaults in August 2026 and stated that the U.S. share of global defaults reached a six-year high. Consequently, underwriting in investment banking increasingly depends on disciplined risk selection and evidence-based judgment.

Europe and the UK

Europe and the United Kingdom show rising average transaction values against an unsettled economic and interest-rate backdrop. In the United Kingdom, PwC estimated that first-half 2026 M&A value totaled £134.7 billion, an increase of 125% from the prior-year period, while transaction volume declined 12.6% to 1,302 deals. The ten largest transactions accounted for more than half of total deal value.

European underwriters therefore face the same concentration concerns as their U.S. counterparts, along with additional legal complexity, currency exposure, and cross-border execution risks. The ECB’s September rate increase also indicates that underwriters should not assume a smooth decline in European financing costs.

Middle East and GCC

Transactions in the Middle East have experienced more stability and resilience than consistency. PwC estimated 272 M&A transactions in the Middle East in H1 2026, 8% less than in the preceding year. In this period, the UAE and Saudi Arabia contributed 65% of total deal volume, and the number of deals in Saudi Arabia was around 74. Technology, media and telecommunications was the busiest industry, with 76 deals.

Regional and sovereign-related capital is still quite powerful. Hence, the underwriting process may consider such factors as strategy and cross-border issues, along with other financial factors, like the currency of the transaction, energy price risk, sovereign counterparties and, increasingly, technology-focused investment opportunities. For deal teams, underwriting in investment banking now requires earlier validation of assumptions and downside cases.

What Is Making Underwriting in Investment Banking More Difficult in 2026?

Scattered data is one of the biggest challenges. Financial data could be spread out in management accounts, audited statements, operating databases, virtual data rooms and third-party databases.

Challenging capital structures need an examination of senior debt, revolving credit lines, subordinated securities, preferred stock and other securities beyond the leverage ratio alone.
Refinance assumptions need more attention. Successful 2026 issuances have long maturities, yet some companies will still need considerable refinancing.

Disruptive trends are hard to forecast. Trends like AI, energy prices, geopolitics, and supply chain changes can affect business operations faster than financial statements can show.
Timelines for transactions have not improved. When due diligence, valuation, financing, and documentation all occur at the same time, more data must be processed without reducing the validity of the process.

Information consistency has also become an underwriting risk. EBITDA in a bank presentation may differ from EBITDA in the operating model; revenue projections may not reconcile with customer-level data; and management adjustments may materially change leverage calculations. These discrepancies require strong analytical skills and thorough review.

Magistral’s Support for Underwriting in Investment Banking

Magistral Consulting supports investment banks, private equity firms, private credit investors, and other financial institutions during underwriting and transaction evaluation. Its analytical support may include financial-statement analysis and spreading, company and industry research, peer and precedent-transaction analysis, financial modeling, scenario and sensitivity analysis, leverage and debt-capacity analysis, investment-banking due diligence, transaction research, preparation of underwriting and investment memoranda, data-room review, and ongoing portfolio or credit monitoring.

The objective is to operate as an extension of the client’s investment or transaction team by providing research and execution support, while final underwriting decisions remain with the client. Used carefully, technology can make underwriting in investment banking faster without weakening professional review.


About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author
Prabhash Choudhary is the CEO of Magistral Consulting. He is a Stanford Seed alumnus and mechanical engineer with 20 + years’ leadership at Fortune 500 firms- Accenture Strategy, Deloitte, News Corp, and S&P Global. At Magistral Consulting, he directs global operations and has delivered over $3.5 billion in client impact across finance, research, analytics, and outsourcing. His expertise spans management consulting, investment and strategic research, and operational excellence for 1,200 + clients worldwide


FAQs


How is AI changing investment banking underwriting in 2026?

AI is primarily reducing the time required for information-intensive tasks rather than replacing underwriting judgment. Tools can extract financial information, review documents, organize diligence materials, and assist with scenario analysis. This allows professionals to spend more time reviewing assumptions and identifying risks. The control framework remains important: outputs must be reconciled with source documents, financial models require quality checks, and ambiguous accounting, legal, or commercial information still requires experienced interpretation.


Which financial metrics are receiving greater attention during underwriting?

Headline leverage remains relevant, but underwriters increasingly examine cash interest coverage, free cash-flow conversion, covenant headroom, liquidity, working-capital requirements and refinancing capacity together. Revenue visibility, customer concentration and recurring versus non-recurring earnings also affect how much confidence can be placed in projected EBITDA. For leveraged transactions, the relationship between leverage reduction, capital expenditure and cash generation can be more informative than a single debt-to-EBITDA figure.


How does underwriting differ between private credit, M&A and equity transactions?

The analytical foundation overlaps, but the risk being evaluated differs. Credit underwriting focuses heavily on downside protection, cash flow, leverage, documentation and repayment capacity. M&A underwriting may place greater emphasis on valuation, synergies, financing structure and integration risk. Equity underwriting also assesses market positioning, earnings quality, investor appetite and valuation support. In each case, sector research, financial modeling and sensitivity analysis help translate transaction assumptions into measurable outcomes.


What work can external underwriting teams support?

External analytical teams can assist with financial spreading, industry research, peer benchmarking, comparable-company analysis, precedent transactions, financial modeling, debt-capacity analysis, scenario testing, data-room review, diligence tracking, and preparation of underwriting or investment materials. They can also perform consistency and source-validation checks. Risk appetite, transaction approval, and final investment or credit decisions should remain with the institution’s authorized professionals and committees.


What are the largest underwriting risks in the current market?

The principal risks are often interconnected: higher-for-longer financing costs can reduce coverage ratios just as weaker growth affects cash generation; aggressive EBITDA adjustments can overstate debt capacity; refinancing assumptions can underestimate future funding costs; and sector disruption can weaken historical relationships between revenue, margins and valuation. Data inconsistency is another material concern because underwriting decisions increasingly rely on information drawn from numerous financial, operational and third-party sources.


Private credit has quietly transformed how risk is structured, priced, and controlled across global capital markets. As private equity sponsors, credit funds, banks, and growth-stage companies rely more heavily on non-bank capital, credit research has shifted from analyzing visible risks to uncovering hidden structural risks.

While public credit is based on ratings, liquidity, and standardised disclosures, private credit sits within tailored legal frameworks, layered capital stacks, and covenant-driven control rights. That evolution has made credit research a structural discipline, now at the core of capital preservation and risk control.

Private Credit Has Changed What Credit Research Actually Does

The public credit market was designed to be transparent. Analysts used rating agencies, trading spreads, standardized contracts, or market behaviour as references to determine risk. In the case of private credit, nearly all these references have been abolished.

From Market-Driven Risk to Structure-Driven Risk: In a Growing Private Credit Universe

The private credit market universe has grown significantly over the past few years. In fact, global private credit assets under management (AUM) exceeded US$3 trillion as of 2025, reflecting growth from approximately US$2 trillion as of 2020.

This is a pointer to why public market-style credit research is inadequate. As a multi-trillion-dollar asset class for private credit, the risk is no longer about being transparent or well-known on public markets. It is now a question of structured design. Moreover, credit market research has to transition from reading market opinions to understanding uniquely structured deal memoranda.

Capital Structures That Public Credit Was Never Built to Analyse 

In today’s private credit transactions, sophisticated financing arrangements are common. These arrangements include unitranche loans, second-lien facilities, mezzanine loans, PIK toggle bonds, and hybrid equity components. These are not evaluated by traditional credit analysis.

In private credit, research must pose the question: Just how does the value flow through the layers, and how does the inter-creditor rights mechanism split the recovery proceeds, and where are the losses? This has become mainstream, no longer a niche issue, because of the scale of the capital out there.

Covenants as Active Risk Mechanisms in a Competitive Funding Environment

The more complex the structures, the more central the covenant design becomes to risk control. Maintenance covenants, liquidity floors, aggressive EBITDA add-backs, and cure-rights have been among the common lender-protective provisions in private credit deals.

Without public market liquidity or mark-to-market pricing, research teams must stress-test covenant headroom across scenarios, assess breach risk, and model renegotiation or default outcomes.

In particular, with private credit funds managing multi-billion-dollar portfolios, covenant risk no longer remains a side analysis but rather a core determinant of downside.

Operational Risk as a Core Credit Research Input: Early Signals Matter

Operational risk has thus emerged as a focal point within contemporary research, reflecting the growing size of the global private credit industry. As of 2025, the global private credit industry manages more than $3 trillion in assets. Means, even small operational risks can have a significant impact on portfolio performance.

Consequently, stress has emerged in business operations rather than financial statements, compelling credit researchers to shift focus upstream within operational risk monitoring.

Although its reported non-finance corporate default rate remains relatively low, around 1.5%–2.0% in 2024, there has been a sharp increase in amending and restructuring. Consequently, credit analysts now view operational warning signs. Like, customer payment delays, capex pressures, and supplier risk and margin compression as more significant factors than leverage ratios when assessing credit risk.

How Private Credit Is Rewriting Risk Ownership Across Capital Providers

Private credit market evolution is now a dominant force for allocation and resource distribution. Early 2025 data showed the amount under management for global private credit at about 3 trillion USD; this was 2 trillion USD in 2020. Volatility becomes more costly when such a market is operating at this level because even the slightest carelessness is magnified and can affect risk management.

How the Rise of Private Credit Is Reshaping Credit Research

How the Rise of Private Credit Is Reshaping Credit Research

Private Equity and Credit Funds Now Carry Structural Risk

To private equity sponsors and credit funds, the risk is no longer solely about whether a borrower defaults but resides in covenant engineering, capital-stack hierarchy, and recovery sequencing. Recent data shows that in 2025, more deals, especially in middle-market direct lending, are based on layered structures and flexible interest/payment terms, such as PIK toggles or covenant-lite provisions. With this level of complexity, funds that invest in rigorous, structure-aware research can better manage hidden downside and deliver stronger risk-adjusted returns.

Banks Face a Precision Problem, Not a Volume Problem

This growing private credit market increasingly poses unique risks and opportunities for banks as traditional lenders and institutional lenders. These dynamics play out in custom-made financings that sit outside the boundaries of typical business loans and bond issuances. Based on a 2024–2025 industry study, global private credit outstanding has grown from approximately US$1 trillion in 2020 to around US$1.6 trillion as of early 2024.The CAGR here stands at around 16%.

This rapid expansion generates pressure on traditional credit risk frameworks. Conventional credit analysis templates are incapable of analysing structural risk, covenant vulnerability, or recovery profiles. This necessitates intensive credit research that is heavily dependent on the underlying credit structure.

Founders Are Now Judged on Transparency, Not Just Growth

Today, for borrowers, especially in the middle market and leveraged firms, access to private credit significantly relies on whether operational transparency and reporting discipline are available. Lenders increasingly expect visibility of operating metrics, liquidity cycles, and cash-flow behaviour in real-time. Recent market surveys of private credit funds in India, a microcosm of broader global trends, reported that private credit investments reached US$9.0 billion for H1 2025, up by 53% over H1 2024.

But it was only such deals that had robust cash-flow discipline and sharp covenant compliance frameworks that were granted. In such an environment, founders need to run their businesses with clear alignment to lender expectations. Credit research no longer depends solely on past performance. It also evaluates forward-looking structural and operational integrity.

Credit Research as Strategic Infrastructure

What was non-core is now strategic. Increasingly, as private credit grows into a multi-trillion-dollar asset class, deal complexity continues to rise. Private equity players are embracing hybrid approaches, where in-house decision-making meets external research facilitation. This shift enables enhanced downside research, constant covenant monitoring, and analysis of complex structures. It achieves this without expanding headcount, a key differentiator for best-in-class managers.

What Lies Ahead for Credit Research

Private credit development outpaces all available analysis infrastructure that attempts to study it. By 2030, global private credit assets under management are expected to reach $4.5–$6 trillion, nearly doubling from 2024 levels and increasing exposure to opaque, highly customized structures that render traditional research methods insufficient.

The Structural Shift Redefining Credit Research

The Structural Shift Redefining Credit Research

Future research on credit for PE firms, credit funds, banks, and entrepreneurs in the future would be predictive in nature and would be continuous. More than 60% of private credit investors are already increasing their investments in data analysis, modelling, and outsourced research, and this trend is expected to accelerate in the future. Organizations that treat credit market research as a form of infrastructure would be safeguarding their capital.

How Magistral Supports Modern Credit Research

As credit risk shifts from public markets to private, illiquid, and structured exposures, credit market research has moved beyond rating interpretation. It now focuses on deal-level underwriting, downside protection, and continuous monitoring.

Magistral’s teams integrate financial analysis, legal and structural review, macro sensitivity, and asset-level diligence. This integrated approach supports investment decisions, risk committees, and portfolio monitoring across the credit lifecycle.

Deal-Level Credit Underwriting

Cash-flow modeling, leverage analysis, downside and recovery scenarios for private and structured credit deals.

Covenant and Documentation Analysis

Review of loan agreements, intercreditor terms, security packages, and control rights to assess true downside protection.

Private Credit Due Diligence

Business, borrower, and asset-level diligence for direct lending, unitranche, asset-backed, and special situations credit.

Portfolio Credit Monitoring & Surveillance

Ongoing tracking of covenant compliance, liquidity headroom, performance drift, and early-warning signals.

Recovery & Distressed Credit Analysis

Recovery modeling, restructuring scenarios, enforcement pathways, and control outcomes in downside cases.

Regulatory & Risk Reporting Support

Credit documentation and analytics aligned with regulatory scrutiny, internal risk frameworks, and audit requirements.

About Magistral Consulting

Magistral Consulting has helped multiple funds and companies in outsourcing operations activities. It has service offerings for Private Equity, Venture Capital, Family Offices, Investment Banks, Asset Managers, Hedge Funds, Financial Consultants, Real Estate, REITs, RE funds, Corporates, and Portfolio companies. Its functional expertise is around Deal origination, Deal Execution, Due Diligence, Financial Modelling, Portfolio Management, and Equity Research

For setting up an appointment with a Magistral representative visit www.magistralconsulting.com/contact

About the Author

Aman is an investment-research specialist with 5+ years of experience across business and investment research, including 2+ years with Big Four firms like KPMG. A Stanford Seed alumnus with an MBA in Finance and a Bachelor of Commerce (Hons) from University of Delhi, he focuses on private equity, venture capital, and renewable energy sectors. He leads project teams at Magistral Consulting, delivering financial research, due diligence, deal sourcing, and M&A support, while driving strong process management and analytics. His blend of attention to detail, strategic thinking, and dynamic execution enables him to turn complex data into actionable investment insights.

FAQs

What differentiates Magistral from traditional research providers?

Magistral combines investment-grade analysis with execution depth, delivering bespoke, decision-ready insights rather than templated research.

How does Magistral integrate with client teams?

Magistral operates as an embedded extension of investment and risk teams, aligned to internal IC standards, timelines, and governance processes.

How does Magistral approach credit research differently today?

Magistral designs credit research for private markets, focusing on deal-level underwriting, downside protection, and long-hold risk rather than market pricing signals.

Can Magistral support ongoing portfolio credit monitoring?

Yes. Magistral provides continuous credit surveillance, covenant tracking, early-warning indicators, and periodic risk reviews for private credit portfolios.